Can a Credit One Bank Hardship Program Help With Credit Card Payments?
A Credit One Bank hardship program or other account-specific payment arrangement may be worth exploring when reduced income, unexpected expenses or another financial setback makes your Credit One credit card payment difficult to manage.
Credit One Bank does not publicly advertise one universal hardship plan with identical payments, interest rates and program lengths for every cardholder. Therefore, consumers experiencing financial difficulty should contact Credit One directly and ask what assistance may currently be available for their account.
If your Credit One Bank credit card debt represents only one part of a larger debt problem, nonprofit credit counseling can also help you review your other credit cards, monthly payments, income and household expenses.
Nonprofit Credit Counseling Since 2001
How to Ask About Credit One Bank Payment Assistance
If you expect difficulty making your Credit One payment, contact the bank as soon as possible. Explain what changed financially and ask whether Credit One Bank payment assistance or another account-specific repayment option may be available.
Before calling, review your monthly income and essential expenses. Knowing how much you can realistically afford may make it easier to discuss possible payment arrangements with a representative.
Credit One Bank currently lists this toll-free number for cardmember customer service.
You can also use the customer-service information printed on your Credit One card or monthly billing statement.
Sign in online or through the Credit One mobile app to review balances, payments and current account information.
How Does a Credit One Bank Hardship Program Work?
Credit One does not publicly publish one standard hardship program with a guaranteed payment, APR or program duration for every credit card account. Consequently, the assistance available may depend on your account status and individual circumstances.
When you contact customer service, explain that you are experiencing financial difficulty and ask what Credit One Bank hardship assistance may currently be available. If a payment arrangement is offered, request the terms before deciding whether to accept it.
Specifically, ask how the arrangement affects your required payment, interest rate, fees, available credit and account status. In addition, find out what happens when the assistance period ends.
Do not assume that a particular rate or payment reduction applies to your account. Credit One's publicly available customer-service information does not promise one universal hardship APR or monthly-payment reduction.
3 Questions to Ask About Credit One Bank Hardship Assistance
A Credit One credit card hardship program or account-specific arrangement could provide breathing room. However, understanding the complete terms is important before agreeing to a repayment option.
What Will My New Payment Be?
Confirm the amount you will need to pay, when the new payment begins and whether it changes during or after the arrangement.
Will My APR or Fees Change?
Ask whether the interest rate, late fees or other account charges change while you participate in the arrangement.
What Happens to My Credit Card?
Find out whether charging privileges remain available, the credit limit changes or the account will be restricted or closed.
A Credit One Bank Hardship Program and Other Ways to Address Debt
Your next step depends on your Credit One balance, APR, household budget and whether this account represents most of your debt or only one of several credit cards.
Work Directly With Credit One
If your Credit One card is the primary problem, contact the bank and ask whether an account-specific Credit One Bank payment plan may be available.
Continue Paying on Your Own
If your budget supports larger payments, calculate whether increasing your monthly payment could help you repay the balance within a reasonable period.
Review a Debt Management Program
If several high-interest credit cards are putting pressure on your budget, nonprofit credit counseling may provide a coordinated repayment approach for eligible accounts.
Credit One Credit Protection vs. Hardship Assistance
Credit One also offers an optional Credit Protection Program. This is different from contacting the bank after financial problems arise and asking about hardship or payment assistance.
Under Credit One's current program agreement, eligible enrolled cardholders may receive minimum-payment benefits for qualifying involuntary unemployment or disability. Benefits can apply for up to six qualifying payments, subject to the program's terms and requirements.
Because Credit Protection is an optional paid product, do not assume that you are enrolled. Check your account or contact Credit One to determine whether you previously purchased the coverage.
When a Credit One Bank Hardship Program May Not Be Enough
A Credit One Bank hardship program may make one account easier to manage without solving a larger monthly cash-flow problem. For example, you may also owe money to several other credit card companies.
In that situation, nonprofit credit counseling can help you review multiple debts together instead of concentrating only on your Credit One payment.
Credit One Bank Hardship Program or a Debt Management Program?
If Credit One Bank hardship assistance does not address your overall debt situation, nonprofit credit counseling provides another repayment option to consider.
Through a Debt Management Program, eligible participating creditors may provide reduced interest rates, lower required payments or other concessions. Qualifying clients generally make one scheduled program payment, and the counseling agency distributes funds to participating creditors.
A traditional DMP is not another debt-consolidation loan. Instead, eligible balances are repaid through a structured program without borrowing additional money.
Credit One debt management program eligibility and final creditor terms depend on the individual account and Credit One's current guidelines. Consequently, a particular interest rate, payment reduction or payoff period cannot be guaranteed.
DebtWave's Experience With Credit One Bank Credit Card Accounts
DebtWave analyzed Credit One credit card accounts enrolled in its Debt Management Program from 2010 through 2024. These historical results describe what occurred within that group; future creditor terms and individual outcomes may differ.
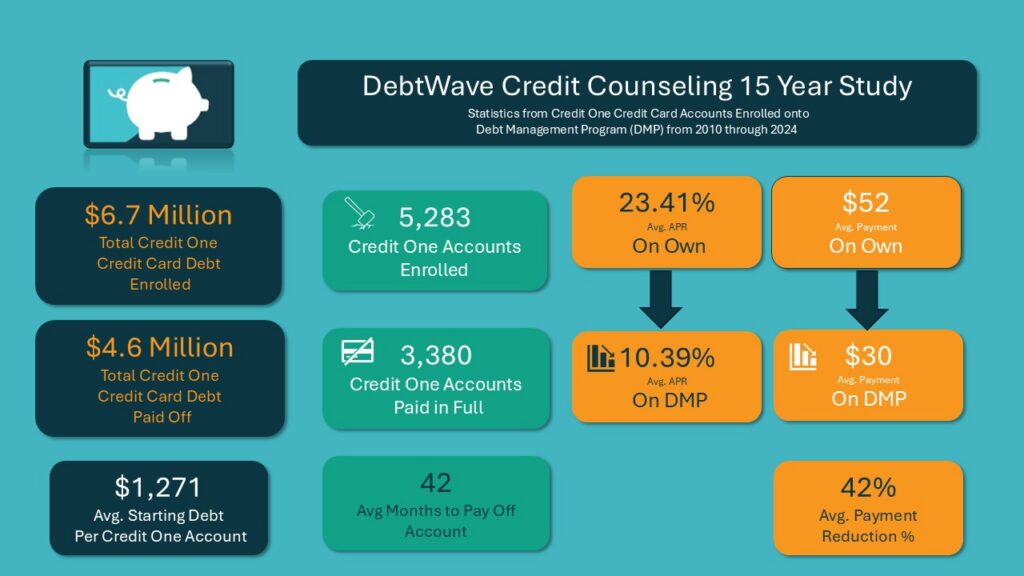
Historical DebtWave analysis of Credit One accounts enrolled from 2010 through 2024. The study included approximately $6.7 million in enrolled Credit One credit card debt, an average starting balance of $1,271 and an average payment reduction of 42%. Historical averages and outcomes do not guarantee future creditor terms or individual results.
Credit One Bank Hardship Program vs. a Debt Management Program
A Credit One Bank hardship program and a Debt Management Program may both address payment pressure, but they serve different purposes. One focuses on your Credit One account, while the other may coordinate repayment across several eligible creditors.
| Feature | Credit One Assistance | Debt Management Program |
|---|---|---|
| Who provides it? | Credit One Bank | Nonprofit credit counseling agency |
| Accounts addressed | Individual Credit One account | Multiple eligible participating creditors may be included |
| New loan required? | No | No |
| Payment or APR changes? | Depends on any account-specific option Credit One offers | Depends on participating-creditor guidelines |
| Budget and debt review? | Not the primary purpose | Included in the credit counseling process |
| Multiple creditors? | Generally focused on the Credit One account | Multiple qualifying accounts may be coordinated |
Estimate Your Credit One DMP Payment and APR
Use DebtWave's Debt Management Plan Calculator to compare your current credit card balances, payments and APRs with estimated program terms.
Calculator results are estimates. Actual Credit One eligibility, interest rates, payments and creditor concessions depend on the individual account and current creditor guidelines.
Why Consider DebtWave for Credit One Bank Credit Card Debt Relief?
DebtWave Credit Counseling, Inc. is a 501(c)(3) nonprofit organization that has provided credit counseling, financial education and Debt Management Programs since 2001.
In addition, DebtWave is a member of the National Foundation for Credit Counseling. A DebtWave counselor can help you review your Credit One debt alongside your other unsecured accounts and household budget.
Speaking with DebtWave does not require you to enroll in a DMP. Instead, you can first compare your existing repayment strategy, direct creditor assistance and potential Debt Management Program terms.

NFCC Member Agency
DebtWave is listed in the National Foundation for Credit Counseling member-agency directory.
Credit One Bank Hardship Program FAQs
Does Credit One Bank have a hardship program?
Credit One does not publicly list one universal hardship plan with standard terms for every cardholder. If you are having difficulty making payments, contact Credit One customer service and ask what account-specific assistance may currently be available.
What is the Credit One Bank hardship phone number?
Credit One Bank currently lists 1-877-825-3242 as its toll-free credit card customer-service number. You can also use the number printed on the back of your card or billing statement.
Should I call Credit One before I miss a payment?
Contacting your creditor early can give you more time to understand available options. Explain what changed financially, when you expect the problem to improve and how much you believe you can realistically pay.
Can Credit One Bank lower my monthly payment?
Any Credit One minimum payment help depends on the individual account and whatever assistance Credit One makes available. The bank does not publicly guarantee one reduced payment for every cardholder.
Can Credit One lower my interest rate?
An account-specific arrangement could potentially change your account terms, but Credit One does not publicly guarantee one hardship APR. If a lower rate is offered, confirm the exact APR and how long it will remain in effect.
What is the Credit One Credit Protection Program?
Credit Protection is an optional paid product offered by Credit One. Under the current agreement, qualifying enrolled cardholders may receive minimum-payment benefits after certain events such as involuntary unemployment or disability. It is separate from requesting hardship assistance from customer service.
Does Credit One Credit Protection cover unemployment?
The current Credit Protection agreement includes qualifying involuntary unemployment as a covered event, subject to the program's definitions, eligibility requirements and limitations.
Will applying for Credit One hardship assistance hurt my credit?
Simply asking about assistance does not determine the credit impact. What happens can depend on your existing account status, the arrangement you accept, whether the account is restricted or closed and how payments are reported. Ask Credit One about account reporting before enrolling.
Will Credit One close my card if I enter a hardship plan?
Account treatment can vary. Before accepting an arrangement, ask whether your charging privileges will remain available, whether your credit limit will change or whether the account will be closed.
Does a Credit One hardship program forgive credit card debt?
Hardship assistance generally focuses on making repayment more manageable rather than automatically eliminating the balance. Likewise, a traditional Debt Management Program generally focuses on repaying enrolled balances rather than negotiating the principal down through debt settlement.
Can a Credit One card be included in a Debt Management Program?
Eligible Credit One accounts may be able to participate in a nonprofit Debt Management Program. However, participation, interest rates, payments and other concessions depend on current creditor guidelines and the individual account.
Will my Credit One card be closed if I enroll it in a DMP?
Credit card accounts enrolled in a Debt Management Program are generally closed or restricted from additional purchases. Specific account treatment may vary according to creditor requirements.
Is a Credit One debt management program a consolidation loan?
No. A traditional Debt Management Program does not replace your balances with a new loan. Instead, eligible debts are repaid through a structured program administered by a nonprofit credit counseling organization.
What if I have Credit One plus several other credit cards?
A nonprofit credit counseling session can review several unsecured creditors together. This may be useful when your Credit One payment represents only one part of a larger monthly debt burden.
How can I estimate my Credit One payoff time?
Use DebtWave's Credit Card Payoff Calculator to compare your balance, APR and proposed payment and estimate how long repayment may take.
How can I estimate a Credit One DMP payment?
Use DebtWave's Debt Management Plan Calculator to compare your current credit card terms with estimated Debt Management Program terms. Actual Credit One terms may differ from the calculator estimate.
Compare Your Credit One Bank Credit Card Debt Relief Options
If your Credit One payment has become difficult to manage, start by asking Credit One about assistance available for your account. However, when several credit cards are straining your budget, reviewing the complete situation may be more useful than addressing only one balance.
DebtWave can provide a free financial review and help you compare paying the debt yourself, a Credit One Bank hardship program and a nonprofit Debt Management Program.
DebtWave Credit Counseling, Inc. is not affiliated with or endorsed by Credit One Bank, N.A. Credit One Bank names and trademarks belong to their respective owner. Credit One payment-assistance programs, eligibility, Credit Protection benefits and account terms may change. Debt Management Program eligibility, creditor participation, interest rates, payments and concessions vary by creditor and individual account. Historical results do not guarantee future outcomes. DebtWave is a 501(c)(3) nonprofit organization and does not lend money.