Free Credit Counseling Services & Credit Card Debt Help
Credit Counseling Services from DebtWave can help you understand credit card balances, monthly expenses and repayment alternatives before making a financial commitment.
During a free, one-on-one session, a counselor can review your income, debts and goals. Afterward, DebtWave provides a personalized Financial Analysis Report to help you understand the next steps.
You can explore budget changes, creditor hardship options and a Debt Management Program without applying for a new loan or committing to enrollment.
Free initial consultation. No new loan required for a DMP. No obligation to enroll.
What Are Credit Counseling Services?
Credit counseling helps consumers organize debts, understand spending and create a more realistic household budget. It is a conversation about your options, not a loan application.
According to the Consumer Financial Protection Bureau, credit counselors can help with budgeting and money management, credit reports and repayment planning.
A counseling session can be useful before payments become late, while you are considering consolidation, or when minimum payments are taking too much of your income.
Will Credit Counseling Hurt My Credit Score?
Simply receiving credit counseling does not directly lower your credit score. If a counselor reviews your credit through a soft inquiry, that inquiry does not affect your score.
However, choosing a Debt Management Program afterward may affect your credit profile. Participating revolving accounts generally need to close, and changes in available credit, balances and payment history can affect scores.
Discuss these distinctions with your counselor before choosing a repayment strategy.
Who Can Benefit From Credit Counseling?
You do not need to be behind on bills to speak with a credit counselor. Many people seek help while their accounts are current but high interest makes it hard to reduce balances.
Counseling can also help when your income changes or multiple payment due dates put pressure on the household budget.
- High-interest credit cards or only making minimum payments
- Several credit card payment dates every month
- A changing income or rising household expenses
- Considering a consolidation loan or debt settlement
- Unsure whether a Debt Management Program fits
What Happens During a Credit Counseling Session?
An initial credit counseling session generally takes about an hour, depending on your circumstances. First, your counselor reviews your goals, household income, essential expenses and outstanding debts.
Next, you look at current monthly payments and discuss what is affordable. Finally, the counselor explains possible approaches, answers questions and helps you identify useful next steps.
There is no requirement to enroll in a Debt Management Program simply because you complete counseling.
Receive a Personalized Financial Analysis Report
After your counseling session, DebtWave emails a personalized Financial Analysis Report. It summarizes your budget, debts and potential next steps so you can review the information without trying to remember every detail of the call.
Your Report May Include
- Monthly income and expense analysis
- Budget categories and spending percentages
- Summary of debts and liabilities
- Debt-to-income and debt-to-credit ratios
- Credit score information when available
- Review of possible repayment approaches
- Creditors that may qualify for a DMP
- Estimated DMP payments and interest rates
- Current versus estimated DMP payments
- Projected interest savings and payoff time
- Personalized recommendations and next steps
The sample uses fictional information. Actual reports and creditor estimates vary.
What Financial Information Will Your Counselor Review?
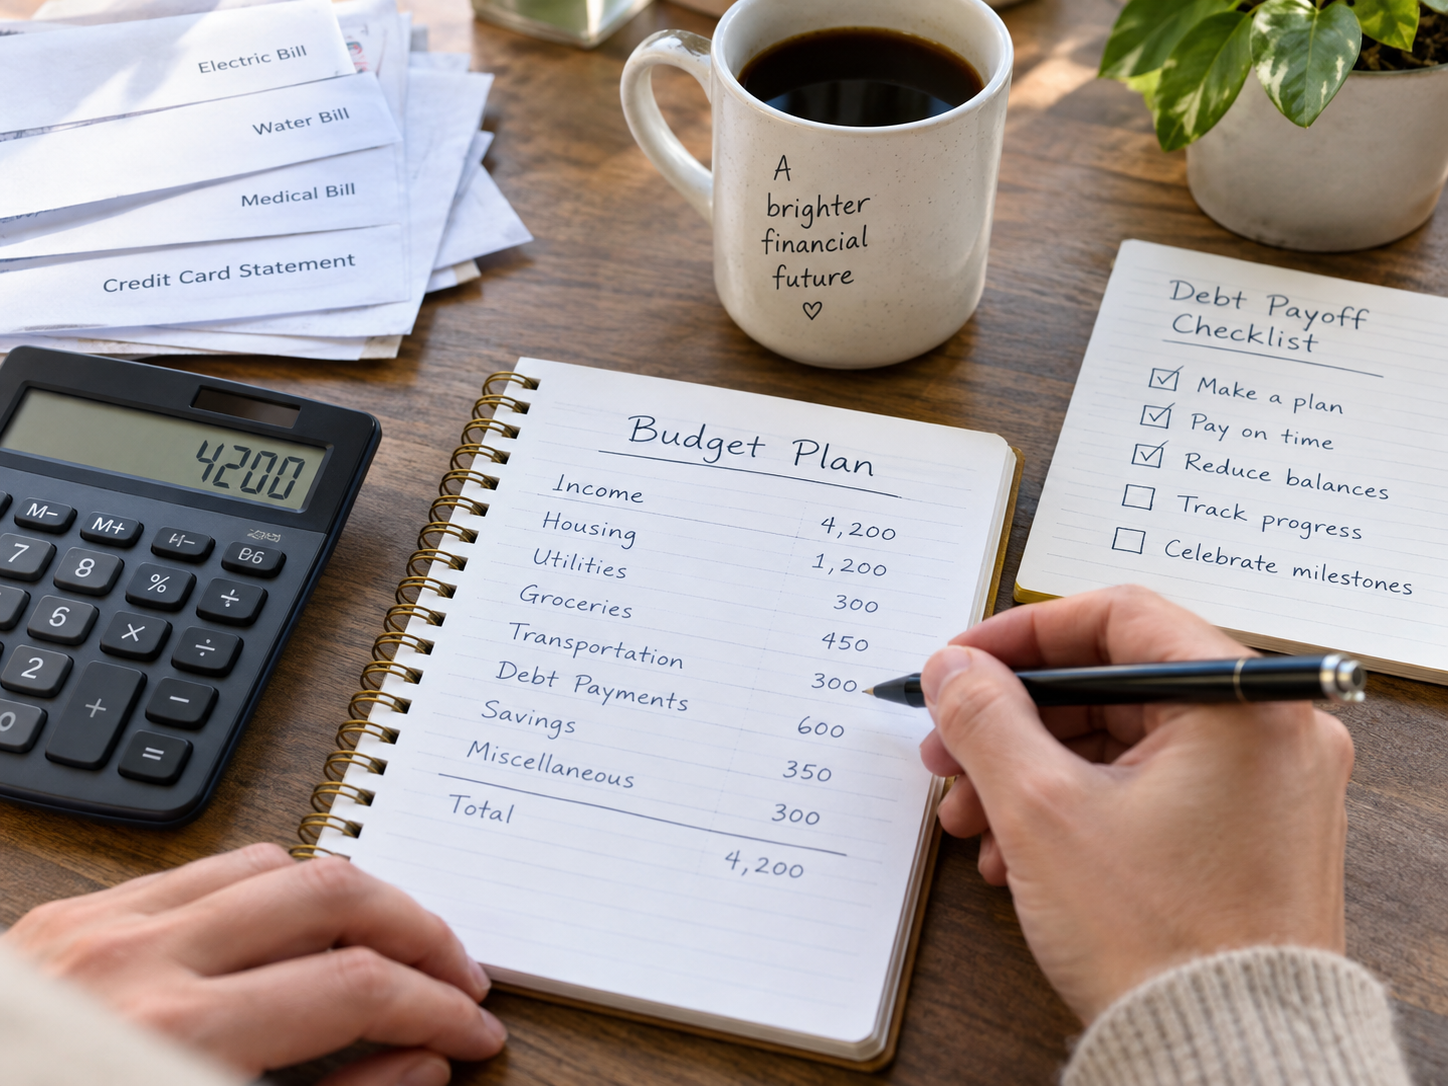
A clear picture of your finances makes it easier to discuss useful strategies. Recent account statements can help, but you can still begin the conversation without every document.
- Monthly take-home income and housing costs
- Credit card balances, APRs and minimum payments
- Vehicle loans, student loans and medical bills
- Food, utilities, insurance and communications
- Other recurring expenses and financial goals
What Debt Repayment Options Will a Counselor Discuss?
A counseling session should consider your personal circumstances rather than automatically pushing one solution. The Federal Trade Commission recommends considering an agency’s services, fees and counselor qualifications.
| Option | How It May Work |
|---|---|
| Pay Debt on Your Own | Budget and make extra payments toward your highest-interest or smallest balances. |
| Creditor Hardship Programs | Ask creditors about temporary interest or payment relief. |
| Debt Management Program | Repay eligible unsecured debt through a structured plan with possible creditor concessions. |
| Consolidation Loan | Take a new loan if you qualify for favorable terms and understand the total cost. |
| Debt Settlement | Consider the risk of delinquencies, collections, credit harm and taxes. |
| Bankruptcy | Speak with a qualified attorney if repayment is not realistic. |
What Is a Debt Management Program?
A Debt Management Program (DMP) may help some consumers repay eligible unsecured debts through one scheduled program payment. DebtWave distributes payments to participating creditors according to the plan.
Some creditors may offer lower rates or other concessions, but eligibility and terms vary. A DMP is not a consolidation loan, and revolving accounts enrolled in the plan generally must be closed or restricted.
The counselor can review possible fees, estimated payments and account eligibility before you decide whether to enroll.
Estimate Your Debt Management Plan Payment & APR
If high-interest credit card balances are a main concern, select a creditor and enter the current balance, APR and minimum payment in DebtWave’s DMP calculator. Results are estimates, not guaranteed offers.
Important: The existing live page contains an interactive Gravity Forms calculator and lead form. Keep the original Gravity Forms widget on the WordPress page; this replacement HTML intentionally does not recreate its fields or consent text.
How Does the Credit Counseling Process Work?
Tell Us About Your Financial Goals
Discuss lowering payments, reducing balances or understanding your options.
Review Your Income and Expenses
Look at the budget remaining after essential expenses.
Analyze Your Debts
Review balances, rates, account status and minimum payments.
Compare Possible Solutions
Discuss advantages, limitations and risks of available strategies.
Receive Your Financial Analysis Report
Get your personalized summary by email after the session.
Choose What You Want to Do
Decide whether to take action yourself or explore another program.
Is DebtWave Credit Counseling Really Free?
Yes. DebtWave offers its initial credit counseling session without charge and does not require DMP enrollment.
If you later consider a program that involves setup or monthly service fees, your counselor can explain those costs before you decide whether to proceed. You may use counseling simply to understand your situation and available options.
Why Choose a Nonprofit Credit Counseling Organization?
DebtWave Credit Counseling, Inc. is a nonprofit organization focused on consumer budgeting, credit education and repayment options.
Nonprofit status by itself is not enough to evaluate an agency. Ask about counselor qualifications, fees, the services offered and educational resources. A trustworthy provider should explain options before requesting a commitment.
Credit Counseling for Military Members and Families
PCS moves, deployments, changing allowances and transitions to civilian employment can place additional pressure on a military household budget.
Service members may also have legal protections, including the Servicemembers Civil Relief Act, that deserve review before changing the treatment of qualifying debt.
A credit counseling session can help you organize monthly expenses while evaluating benefits and resources available to military families.
How to Prepare for Your Credit Counseling Session
You do not need perfect records to get started. Before your appointment, gather what you can, including recent credit card statements, approximate monthly take-home income, housing costs and financial goals.
- Current credit card balances and APRs
- Minimum monthly payments and due dates
- Housing, transportation and utility costs
- Insurance, groceries and other household expenses
- Student loan and personal loan obligations
- Questions you want to ask the counselor
If a number is missing, your counselor can help you identify what is most important.
Talk With a Credit Counselor About Your Debt
If high interest or monthly expenses make it difficult to get ahead, a free session can help clarify your choices. No new loan or DMP enrollment is required to receive counseling.
Credit Counseling Services FAQs
Frequently Asked Questions About Credit Counseling Services
What does a credit counselor do?
A counselor reviews income, debts, expenses and goals, then helps you compare practical budgeting and repayment options.
How long does a credit counseling session take?
An initial session generally takes about an hour, though circumstances vary.
Will credit counseling lower my credit score?
Simply completing counseling does not directly affect your score. Decisions made afterward, such as enrolling in a DMP, can affect your credit profile.
Do I have to be behind on my credit cards?
No. You may receive counseling while accounts are current.
What do I receive after my session?
DebtWave emails a personalized Financial Analysis Report summarizing reviewed finances and potential next steps.
Financial Analysis Report and Debt Management Questions
Can I see a sample Financial Analysis Report?
Yes. View the fictional sample report to understand its format.
Does credit counseling mean I have to enroll in a DMP?
No. A DMP is an optional strategy; counseling does not require enrollment.
Can a DMP lower credit card interest rates?
Participating creditors may offer concessions, but terms and eligibility vary.
What types of debts can counseling help with?
Counselors can discuss credit cards, personal loans, student loans, medical debt and household obligations; solutions depend on debt type.
Is credit counseling the same as debt settlement?
No. Counseling focuses on budgets and repayment choices, while settlement attempts to resolve debts for less than owed and carries different risks.
Debt Management Plan Calculator Questions
Can I use the DMP calculator before talking with a counselor?
Yes. Enter a creditor, balance, APR and payment to see an estimate.
Does using the calculator affect my credit score?
No credit check is required simply to enter information into the calculator.
Are the calculator results guaranteed?
No. Estimates depend on creditor guidelines and eligibility at the time of review.
Can a counselor review all my creditors together?
Yes. A complete session looks at multiple debts along with your household budget.
Start With a Free Credit Counseling Session
You do not need to decide on a debt solution before contacting DebtWave. Review your budget, credit card debts and financial goals with a counselor, then use the Financial Analysis Report to consider your next steps.
Free consultation. No new loan. No obligation to enroll.