If you are searching for San Diego debt consolidation, the most important question is not simply how to combine several payments into one. Instead, you need to determine which repayment strategy can help you reduce debt without creating a bigger financial problem.
Debt consolidation can describe several different options, including a personal loan, balance transfer credit card, Debt Management Program or debt settlement. Although each approach may simplify your finances, the costs, risks and qualification requirements vary considerably.
DebtWave Credit Counseling, Inc. is a nonprofit credit counseling organization located in San Diego County. We do not lend money. However, our certified counselors can help you review your budget, compare debt consolidation options and determine whether a structured repayment plan may fit your situation.
Most importantly, you can start with free credit counseling and no obligation to enroll.

What Does San Diego Debt Consolidation Actually Mean?
Debt consolidation generally means reorganizing multiple debts so they become easier to manage. However, not every consolidation strategy works the same way.
For example, a debt consolidation loan replaces several balances with a new loan. A balance transfer moves debt onto another credit card, while a Debt Management Program keeps the debts with your existing creditors and organizes eligible accounts into one scheduled program payment.
Meanwhile, debt settlement follows a completely different strategy because it attempts to resolve debts for less than the full balance. Therefore, you should understand exactly what a company means when it advertises “debt consolidation.”
1. Debt Consolidation Loans in San Diego
A traditional debt consolidation loan combines several debts into one new loan. Typically, you borrow enough money to pay off selected credit cards and then make payments on the new loan.
For some San Diego consumers, that approach can make sense when the new APR and total borrowing costs are substantially lower. However, approval often depends on your credit, income and existing financial obligations.
Additionally, lenders may charge origination fees or extend the repayment period to create a lower monthly payment. Therefore, compare the total amount you will repay rather than focusing only on the monthly payment.
The Consumer Financial Protection Bureau explains important debt consolidation considerations, including promotional rates, repayment periods and the possibility of accumulating additional credit card debt.

Possible Advantages
- One loan payment instead of several credit card payments
- A lower APR may reduce interest expense
- A fixed repayment schedule can provide a clear payoff date
- Paying off revolving balances may simplify monthly budgeting
Possible Drawbacks
- You must qualify for the new loan
- Origination fees can increase borrowing costs
- A longer term may increase total interest paid
- Available credit can create an opportunity to accumulate new debt
2. Using a 0% Balance Transfer for Debt Consolidation
A promotional balance transfer can temporarily reduce the interest you pay on credit card debt. First, you open or use a card that offers a low introductory APR and transfer qualifying balances to it.
During the promotional period, more of each payment may go toward principal. However, this strategy works best when you can substantially reduce or eliminate the transferred balance before the introductory rate expires.
Additionally, most balance transfers involve a transfer fee, and your credit limit may not accommodate every existing balance. After the promotion ends, the remaining debt may carry a much higher APR.
Therefore, calculate how much you must pay each month to eliminate the transferred debt before the promotional period ends.

3. San Diego Debt Consolidation Without a New Loan
If you cannot qualify for an affordable consolidation loan—or simply do not want to borrow more money—a Debt Management Program may provide another way to simplify eligible credit card payments.
A DMP is not a debt consolidation loan. Instead, you make one scheduled program payment to the nonprofit credit counseling organization, which distributes the appropriate amounts to participating creditors.
Depending on current creditor guidelines and account eligibility, creditors may reduce interest rates, lower required payments or provide other concessions. However, DebtWave cannot guarantee a specific APR or payment reduction.
Participating creditors generally require consumers to close revolving accounts included in the program. Nevertheless, you continue repaying what you owe instead of replacing those balances with another loan.
Possible DMP Benefits
- One scheduled payment for participating accounts
- No new debt consolidation loan
- Potential creditor interest-rate concessions
- A structured repayment schedule
- Budgeting and financial guidance from a credit counselor
Important DMP Considerations
- Creditors generally require you to close enrolled revolving accounts
- Creditor concessions vary by account
- Program fees can apply
- You must maintain the required payment schedule
- A DMP primarily focuses on eligible unsecured debt
Start With Free Credit Counseling Before You Consolidate Debt
You do not need to know which option is best before contacting DebtWave. In fact, the purpose of a free credit counseling session is to help you understand your finances before making that decision.
First, a counselor can review your income, household expenses, credit card balances and financial goals. Next, you can compare possible strategies based on your actual budget.
Afterward, DebtWave can provide a personalized financial analysis that helps you understand possible next steps. Therefore, you can evaluate a Debt Management Program without committing to enrollment.
Important: Credit counseling and a Debt Management Program are not the same thing. Credit counseling involves reviewing your finances and available options, while a DMP represents one possible repayment strategy.
4. Debt Settlement Is Different From Debt Consolidation
Debt settlement companies generally try to negotiate balances for less than the full amount owed. Although advertisements may describe that process as debt consolidation or debt relief, the strategy differs significantly from a loan or Debt Management Program.
Typically, settlement programs depend on accumulating money for future settlement offers while accounts become delinquent. As a result, interest, late charges and collection activity can continue while you wait for settlements.
Moreover, creditors can pursue collection efforts or lawsuits, and forgiven debt can create tax consequences in some circumstances. Missed payments and charged-off accounts can also significantly affect your credit.
Therefore, carefully compare those risks with other repayment strategies before choosing debt settlement.
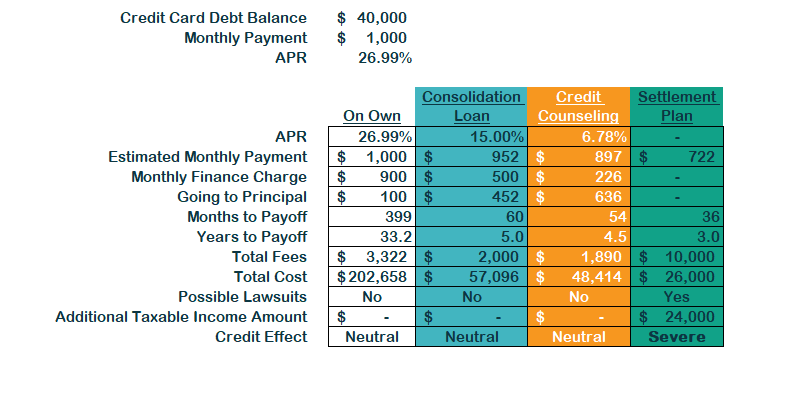
Compare San Diego Debt Consolidation Options
No single debt solution works for every San Diego household. Therefore, compare the cost, qualification requirements and repayment structure before making a decision.
Some options require new credit, while others allow you to repay existing creditors without borrowing more money. Additionally, each approach can affect your finances differently.
| Option | New Credit? | One Payment? | Main Advantage | Key Consideration |
|---|---|---|---|---|
| Consolidation Loan | Yes | Usually | Can combine debt into a fixed loan | Approval, APR, fees and loan term matter |
| Balance Transfer | Usually | Potentially | A promotional APR may reduce short-term interest | Transfer fees and promotional expiration matter |
| Debt Management Program | No | Yes, for participating debts | May reduce creditor APRs without another loan | Creditors generally require enrolled revolving accounts to close |
| Debt Settlement | No | Program deposits may be combined | Attempts to settle for less than the balance owed | Delinquency, collections, fees and possible taxes |
Which Debt Consolidation Approach Fits Your Situation?
A debt consolidation loan may make sense when you qualify for an APR that is meaningfully lower than your current credit card rates. However, compare the total repayment cost before accepting a new loan.
A balance transfer may work better when you have strong credit and can repay the transferred balance during the promotional period. Otherwise, the remaining debt may move to a much higher APR after the introductory offer expires.
Meanwhile, a Debt Management Program may deserve consideration when you want one structured payment without taking out another loan. Debt settlement follows a different strategy and usually carries substantially different risks.
Local Debt Consolidation Help in San Diego County
DebtWave operates from Escondido in San Diego County. Since 2001, our nonprofit organization has helped consumers understand credit card debt, budgeting and repayment options.
Additionally, DebtWave has helped consumers repay more than $325 million in credit card debt through its Debt Management Program. Historical results do not guarantee an individual outcome.
Serving Communities Throughout San Diego County
Consumers can begin the counseling process online or by phone. Therefore, you do not need to travel to an office to review your debt and repayment options.
DebtWave helps consumers throughout San Diego, Chula Vista, Oceanside, Escondido, Carlsbad, Encinitas, San Marcos, Vista, El Cajon, La Mesa, Santee, Poway and surrounding communities.
For additional information about services available to California residents, visit our California credit counseling and debt management page.
Estimate Your Debt Management Plan Payment & APR
Before applying for another debt consolidation loan, see what participating creditor terms could look like through a Debt Management Program.
Enter your creditor, balance, current interest rate and minimum payment below. Then the calculator can estimate a possible DMP payment and APR based on available creditor information.
However, creditor terms can change. Therefore, treat all calculator results as estimates rather than guaranteed offers.
How to Choose the Best Debt Consolidation Option
Start by comparing the solution with your actual financial problem. For example, someone with strong credit and manageable balances may find an affordable consolidation loan or balance transfer.
However, a new loan may not solve the problem when high APRs, multiple cards and a tight monthly budget made the debt difficult to manage. In that situation, nonprofit credit counseling may help you evaluate the entire household budget before borrowing more money.
Meanwhile, consumers facing severe financial hardship may need to evaluate additional options. Those choices could include creditor hardship programs, legal advice or bankruptcy.
Before Choosing a Debt Consolidation Plan, Ask:
- Will the new option actually lower my total cost?
- How much will I pay in fees?
- What happens to the interest rate later?
- How long will repayment take?
- Do I need good credit to qualify?
- Will I still have access to my old credit cards?
- Can I realistically afford the required monthly payment?
- What happens if my income changes?
Will San Diego Debt Consolidation Hurt Your Credit?
The credit impact depends on the type of consolidation you choose. For example, applying for a new loan or balance transfer card may create a hard credit inquiry and a new account.
By contrast, simply speaking with a nonprofit credit counselor does not directly lower your credit score. However, participating creditors generally require you to close revolving accounts included in a Debt Management Program, which can affect credit utilization and other scoring factors.
Debt settlement can create a more serious credit impact when the strategy involves missing creditor payments. Therefore, do not assume every service advertised as debt consolidation affects credit in the same way.
Frequently Asked Questions About San Diego Debt Consolidation
What is the best debt consolidation option in San Diego?
The best option depends on your credit, balances, APRs, income and available monthly cash flow. For example, a consolidation loan may work when you qualify for favorable terms, while a Debt Management Program may make more sense when you want one structured payment without borrowing additional money.
Does DebtWave offer debt consolidation loans?
No. DebtWave Credit Counseling, Inc. is a nonprofit credit counseling organization, not a lender. Instead, DebtWave helps consumers evaluate repayment options and may offer a Debt Management Program for eligible unsecured debts.
Can I consolidate credit card debt without taking out a loan?
Yes. A Debt Management Program can organize participating unsecured debts into one scheduled program payment without replacing those debts with a new loan. Additionally, participating creditors may provide interest-rate or payment concessions under their current guidelines.
Do I need good credit for a Debt Management Program?
A DMP does not work like a traditional loan application because you are not borrowing new money. Instead, the credit counseling agency reviews your debts, household budget and creditor eligibility to determine whether the program may fit your situation.
Debt Consolidation Loans and Credit Counseling Questions
Is a Debt Management Program the same as debt consolidation?
People sometimes describe a DMP as a form of debt consolidation because it can provide one scheduled payment for several participating accounts. However, it is not a consolidation loan because you do not borrow money to pay off your existing creditors.
Is credit counseling free at DebtWave?
Yes. You can begin with a free credit counseling session to review your budget, debts and repayment options. Moreover, speaking with a counselor does not obligate you to enroll in a Debt Management Program.
Can DebtWave help if I have several different credit cards?
Yes. A counselor can review multiple accounts together rather than evaluating only one credit card at a time. Depending on creditor participation and your eligibility, several unsecured accounts may qualify for the same Debt Management Program.
When Should You Consider Debt Consolidation?
Should I consolidate debt before I miss payments?
You do not need to wait until accounts become delinquent to explore your options. In fact, reviewing your finances while your accounts remain current may give you more time to compare loans, creditor hardship programs, balance transfers and nonprofit credit counseling.
Can debt consolidation lower my monthly payment?
It can, but a lower payment does not always mean a better deal. For example, extending repayment over more years may lower the monthly payment while increasing the total amount of interest you pay.
Can debt consolidation lower my interest rates?
Potentially. A qualifying consolidation loan, promotional balance transfer or participating creditor concession through a Debt Management Program may reduce interest costs. However, rates depend on the option you choose and your individual circumstances.
Compare Your San Diego Debt Consolidation Options for Free
You do not have to apply for another loan just to find out whether you have a better way to pay off credit card debt.
Instead, start with a free financial review from DebtWave. A certified credit counselor can help you understand your budget, compare repayment strategies and determine whether a Debt Management Program deserves consideration.
Free credit counseling. No new loan. No obligation to enroll.