Can a OneMain Hardship Program Help With Personal Loan Payments?
A OneMain hardship program or other payment-assistance option may be worth exploring when reduced income, medical expenses, job loss or another financial setback makes your OneMain Financial loan payment difficult to manage.
OneMain Financial tells customers experiencing payment difficulty to contact the company as soon as possible. OneMain states that it works with customers during periods of temporary hardship, although the assistance available depends on the individual account and circumstances.
If your OneMain loan is only one part of a larger debt problem, nonprofit credit counseling can also help you review your other unsecured debts, credit cards, household expenses and overall repayment strategy.
Nonprofit Credit Counseling Since 2001
How to Ask About a OneMain Hardship Program
OneMain Financial specifically asks borrowers who are having difficulty making payments to contact the company. OneMain notes that contacting it sooner may provide more opportunity to discuss ways to get the account back on track.
When you call, explain what has changed financially and ask what OneMain Financial payment assistance may currently be available for your loan. It can also help to know how much you can realistically afford each month.
OneMain lists this number specifically for customers having difficulty making payments.
OneMain also encourages borrowers to contact their local branch to discuss an account-specific payment situation.
OneMain suggests considering whether a different payment due date would better align with your monthly budget.
How Does a OneMain Hardship Program Work?
OneMain does not publicly publish one universal OneMain Financial hardship program with an identical reduced payment, interest rate or duration for every personal loan.
Instead, its current payment-difficulty guidance encourages borrowers to contact OneMain directly. The company states that it works with customers experiencing temporary hardship and wants to identify solutions that fit the customer's needs.
Therefore, if OneMain offers an account-specific arrangement, request the complete terms before accepting it. Ask how much you will need to pay, whether your interest or fees change and how the arrangement affects your loan's remaining repayment schedule.
Before agreeing to assistance: Confirm the required payment, how long the arrangement lasts, whether interest continues to accrue, whether fees change and what payment will be required after the assistance period ends.
3 Questions to Ask About OneMain Payment Assistance
A OneMain personal loan hardship arrangement may provide temporary breathing room, but understanding the full terms can help you evaluate the longer-term impact.
What Will I Need to Pay?
Confirm the required payment amount, when the modified payment begins and whether it changes again later.
What Happens to Interest and Fees?
Ask whether your loan's interest rate or fees change and whether interest continues accruing while assistance is active.
Does the Payoff Date Change?
Find out whether the arrangement extends your loan term, changes future payments or otherwise affects the final payoff date.
A OneMain Hardship Program and Other Ways to Address Your Debt
The approach that fits your situation depends on your OneMain balance, interest rate, monthly budget and whether the personal loan is your only significant debt or one of several unsecured obligations.
Work Directly With OneMain
If the OneMain payment is the primary problem, contact OneMain directly and ask which account-specific options may be available.
Continue Paying on Your Own
If your budget supports additional payments, calculate whether paying extra toward the balance could help shorten the repayment period and reduce interest costs.
Review Nonprofit Credit Counseling
If your OneMain loan is accompanied by several high-interest credit cards or other unsecured debts, nonprofit credit counseling may provide a broader repayment strategy.
When a OneMain Hardship Program May Not Be Enough
A OneMain hardship program may improve one loan payment without resolving a larger monthly cash-flow problem. For example, you may also owe money on several credit cards or other unsecured accounts.
In that situation, nonprofit credit counseling can help you review the complete debt picture rather than treating each account as a separate financial problem.
OneMain Hardship Program or a Debt Management Program?
If direct OneMain payment assistance does not address your overall debt situation, nonprofit credit counseling provides another option to review.
OneMain's own educational materials discuss nonprofit credit counseling as a resource for people struggling with debt. OneMain specifically highlights nonprofit organizations affiliated with the National Foundation for Credit Counseling.
A Debt Management Program may allow eligible participating creditors to provide reduced interest rates, payments or other concessions according to their current guidelines. Qualifying clients generally make one scheduled program payment, and the counseling agency distributes funds to participating creditors.
A traditional DMP is not another debt-consolidation loan. Instead, eligible debts are repaid through a structured program without borrowing additional money.
OneMain debt management program eligibility and final terms depend on the individual loan and OneMain's current creditor guidelines. Therefore, a particular interest rate, payment reduction or payoff period cannot be guaranteed.
DebtWave's Experience With OneMain Financial Accounts
DebtWave analyzed OneMain Financial accounts enrolled in its Debt Management Program from 2010 through 2024. These historical figures show what occurred within that group; however, future OneMain creditor terms and individual outcomes may differ.
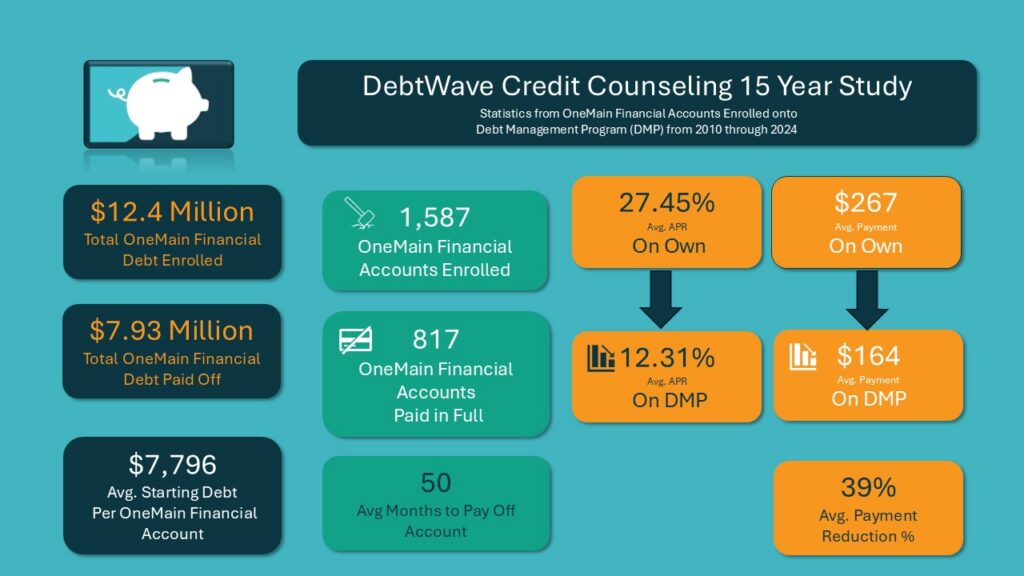
Historical DebtWave analysis of OneMain Financial accounts enrolled from 2010 through 2024. The study included approximately $12.4 million in enrolled OneMain debt, an average starting balance of approximately $7,796 and an average payment reduction of 39%. Historical averages and outcomes do not guarantee future creditor terms or individual results.
OneMain Hardship Program vs. a Debt Management Program
A OneMain Financial hardship program and a Debt Management Program may both address payment pressure, but they work differently. Direct assistance focuses on your OneMain loan, while a DMP may coordinate several eligible unsecured debts.
| Feature | OneMain Assistance | Debt Management Program |
|---|---|---|
| Who provides it? | OneMain Financial | Nonprofit credit counseling agency |
| Accounts addressed | Individual OneMain account | Multiple eligible participating creditors may be included |
| New loan required? | No | No |
| Payment changes? | Depends on any account-specific option OneMain offers | Depends on participating-creditor guidelines |
| Interest-rate changes? | Confirm any change directly with OneMain | Eligible creditors may provide reduced rates |
| Budget and debt review? | Not the primary purpose | Included in the nonprofit counseling process |
| Multiple creditors? | Generally focused on the OneMain loan | Multiple qualifying accounts may be coordinated |
Estimate Your Debt Management Program Payment
Use DebtWave's Debt Management Plan Calculator to compare your current unsecured debts, monthly payments and interest rates with estimated program terms.
Calculator results are estimates. Actual OneMain participation, payments, interest rates and creditor concessions depend on the individual account and current creditor guidelines.
Why Consider DebtWave for OneMain Debt?
DebtWave Credit Counseling, Inc. is a 501(c)(3) nonprofit organization that has provided credit counseling, financial education and Debt Management Programs since 2001.
DebtWave is also a member of the National Foundation for Credit Counseling. OneMain's own financial education specifically discusses nonprofit credit counseling and highlights NFCC-certified agencies as a resource for people struggling with debt.
Speaking with DebtWave does not require you to enroll in a DMP. A counselor can first review your OneMain loan together with your other unsecured debts, monthly payments, income and household expenses.

NFCC Member Agency
DebtWave is listed in the National Foundation for Credit Counseling member-agency directory.
OneMain Hardship Program FAQs
Does OneMain Financial have a hardship program?
OneMain says it works with customers during periods of temporary hardship and asks borrowers experiencing payment difficulty to contact the company. The exact assistance available depends on the account and individual circumstances.
What is the OneMain hardship program phone number?
OneMain currently lists 800-961-5577 for customers having difficulty making payments. You can also contact your local OneMain branch.
Should I contact OneMain before missing a loan payment?
Yes. OneMain encourages borrowers who are having difficulty making payments to contact the company and states that reaching out sooner may provide more opportunity to help get the account back on track.
Can OneMain change my payment due date?
OneMain's payment-difficulty guidance specifically suggests reviewing whether your current due date fits your monthly budget and whether changing the due date could help. Eligibility for a particular change should be confirmed directly with OneMain.
Can OneMain lower my monthly loan payment?
Any OneMain loan payment help depends on the assistance OneMain makes available for the particular account. OneMain does not publish one guaranteed reduced payment that applies to every borrower experiencing hardship.
Can a OneMain hardship program lower my interest rate?
OneMain does not publish one universal hardship APR for every personal-loan customer. If an account-specific arrangement is offered, confirm whether the interest rate changes and how long any modified terms remain in effect.
Is a OneMain hardship program the same as a hardship loan?
No. OneMain describes a hardship loan as a personal loan that may be used to cover unexpected financial challenges. Asking OneMain for help with an existing loan is different because you are seeking assistance with debt you already owe rather than applying for another loan.
Does OneMain support nonprofit credit counseling?
Yes. OneMain has published educational material specifically discussing the benefits of nonprofit credit counseling and recommends looking for reputable nonprofit agencies, including organizations certified through the National Foundation for Credit Counseling.
Can a OneMain loan be included in a Debt Management Program?
Eligible OneMain accounts may be able to participate in a nonprofit Debt Management Program. Acceptance and final terms depend on the specific loan and OneMain's current creditor guidelines.
How does OneMain report accounts handled by credit counseling?
OneMain states that active accounts enrolled with a nonprofit credit counseling service may be reported to the credit bureaus with a comment indicating that the account is being managed by a financial agency. The way that information appears can vary by credit bureau.
Does a OneMain DMP forgive my loan balance?
Generally, no. A traditional Debt Management Program is designed to repay enrolled balances rather than negotiate principal debt down through debt settlement.
Is a OneMain debt management program another consolidation loan?
No. A traditional Debt Management Program does not replace eligible debts with another loan. Instead, qualifying accounts are repaid through a structured repayment program administered by a credit counseling organization.
What if I have a OneMain loan plus several credit cards?
A nonprofit credit counseling session can review multiple unsecured creditors together. This may be particularly useful when your OneMain loan payment represents only one part of a larger monthly debt burden.
How can I estimate a Debt Management Program payment?
Use DebtWave's Debt Management Plan Calculator to compare your current unsecured debt payments and interest rates with estimated program terms. Actual creditor terms may differ from the calculator estimate.
Compare Your OneMain Financial Debt Relief Options
If your OneMain payment has become difficult, start by contacting OneMain and asking about assistance available for your account. If your personal loan is only one part of a larger debt problem, reviewing your complete financial situation may be more useful than addressing one payment by itself.
DebtWave can provide a free financial review and help you compare your current repayment strategy, a OneMain hardship program and nonprofit credit counseling options.
DebtWave Credit Counseling, Inc. is not affiliated with or endorsed by OneMain Financial or its affiliates. OneMain Financial names and trademarks belong to their respective owners. OneMain hardship, payment-assistance and account terms may change. Debt Management Program eligibility, creditor participation, interest rates, payments and concessions vary by creditor and individual account. Historical results do not guarantee future creditor terms or individual outcomes. DebtWave is a 501(c)(3) nonprofit organization and does not lend money.