Henry Wells and William G. Fargo formed Wells Fargo & Company in 1852. Fast forward a hundred years, they became one of the biggest banks in California. At that time, Wells Fargo specialized in consumer credit including home loans, credit cards and car loans.
One of the oldest banks operating in the United States, Wells Fargo became the first major bank to offer online banking services in 1995.
After a century and a half of success, Wells Fargo has successfully found their way into the top 10 list of banks with the largest outstanding balances. According to WalletHub.com, Well Fargo is 8th with a total outstanding balance of $34.7 billion of credit card debt.
What are your options to pay back your Wells Fargo Bank credit card debt?
Facing a large amount of credit card debt can be scary. It’s a constant reminder that we messed up. And chances are neither your formal education nor your family prepared you on how to handle this situation.
There are many debt consolidation options to consider when trying to pay back your Wells Fargo credit card debt. The five main options are:
- Debt Consolidation Loan
- 0% Balance Transfer
- Wells Fargo Internal Hardship Plan
- Debt Management Plan (Credit Counseling)
- Debt Settlement Plan
But the one thing that must be done regardless is putting a stop to your overspending. Each time we use a credit card we are likely purchasing something we can’t afford.
Create a detailed budget outlining all income and all expenses. Revisit this budget periodically and make revisions. Increase income. And decrease expenses.
Wells Fargo Bank Credit Card Hardship program
If you find yourself struggling with credit card debt, hardship programs can help. Contact Wells Fargo Bank directly and let them know about your personal hardship. Provide as many details as possible about your financial situation. They will likely ask about your monthly income and expenses. Telling them that you are simply looking for a lower interest rate and payments won’t suffice. You must have a compelling hardship such as job loss or medical emergency to qualify.
Any concessions granted by Wells Fargo will likely be temporary. A lower interest rate will likely last less than 12 months. Take advantage of that time and attack your debt with extra payments. Some creditors might reduce your credit limit or even close your card once they approve you on their hardship plan.
If you have no luck getting concessions or want more long-term benefits, credit counseling is your next best option. Wells Fargo works very well with nonprofit organizations offering their clients interest rates usually below 10%. Payments typically get lowered as well. Your credit card will be closed on their debt management program. This can be viewed as a good thing for some as the temptation to continue using the card is eliminated.
DebtWave has been helping Wells Fargo clients for more than 20 years
DebtWave has worked with various credit card accounts, including Wells Fargo, since 2002 helping clients pay off debt at lower interest rates. Most clients add other credit cards to their plan such as Citibank and Chase accounts. Clients make payments via ACH either monthly, semi-monthly, weekly or biweekly and then DebtWave disburses payments to their creditors. Most clients complete their program and become debt free in less than 5 years. DebtWave has a 68% successful completion rate.
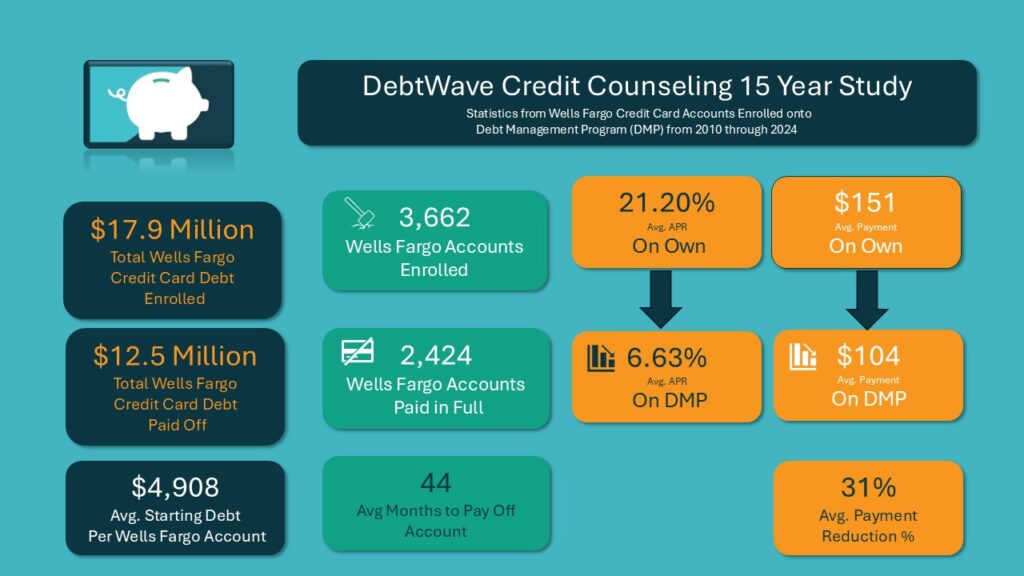
From 2010 to 2024, DebtWave has helped Wells Fargo clients with nearly $17.9 million of total credit card debt. 3,662 Wells Fargo accounts onto our program during that time with an average balance of $4,908. Many clients witnessed their interest rates drop drastically along with a reduction in monthly payments.
Here are some additional stats from these clients:
The Dream of Getting Out of Debt on Your Own is Possible
Paying back your credit card debt seems like a daunting task. But it has proven to be achievable by thousands of DebtWave clients. If you would rather tackle the debt on your own, it can be achieved. Create your own plan. The first step is lower interest rates. High interest rates (25-30% APR) on credit cards makes it very difficult. This would require you to double or triple your minimum payments to make progress.
If you have your rates reduced to less than 10%, then use a payoff calculator or google spreadsheet to create a plan. Find ways to increase income and reduce expenses. Stay motivated and refrain from using cards again. Build an iron clad budget that accounts for all expenses.