If your JCPenney credit card payment has become difficult to manage, you may be searching for a JCPenney hardship program that could provide financial relief. Synchrony Bank issues both the JCPenney Credit Card and JCPenney Mastercard, so cardholders experiencing payment difficulty should contact JCPenney Credit Services about account-specific assistance.
However, trouble paying your JCPenney account may represent only one part of your financial situation. You may also have balances with Chase, Citi, Capital One, Discover, American Express, Wells Fargo, Bank of America, or other creditors.
In that situation, a DebtWave Debt Management Program may provide a broader approach. DebtWave can review your JCPenney account alongside your other eligible unsecured debts.
Does JCPenney Have a Hardship Program Through Synchrony?
Both the JCPenney Credit Card and JCPenney Mastercard are issued by Synchrony Bank. Therefore, consumers searching for a JCPenney hardship program should generally contact JCPenney Credit Services about financial difficulty with the account.
Synchrony encourages customers experiencing payment hardship to contact the company and discuss their circumstances. However, Synchrony does not publicly promise one identical hardship payment, reduced APR, or repayment period for every JCPenney cardholder.
Consequently, ask about the specific assistance available for your account rather than relying on terms another consumer may have received.
How to Contact the JCPenney Hardship Program
JCPenney currently lists 1-800-542-0800 for JCPenney Credit Card account questions. Therefore, customers with the traditional store card can call that number to discuss credit-related or account-related concerns.
If you have the JCPenney Mastercard, JCPenney currently lists 1-866-227-5213 for Mastercard Credit Services.
When you call, explain that you are experiencing financial hardship and that the required payment has become difficult to afford. Then, ask what payment-assistance or hardship options may currently apply.
Who Issues the JCPenney Credit Card?
Synchrony Bank issues the JCPenney Credit Card and JCPenney Mastercard. As a result, Synchrony manages the credit relationship even though the cards carry the JCPenney brand.
Therefore, a salesperson or customer service employee at a JCPenney store generally cannot determine the hardship terms available for your credit account.
For current card information and account access, visit Synchrony's official JCPenney Credit Card page.
Make Sure You Know Which JCPenney Card You Have
JCPenney currently offers both a traditional JCPenney Credit Card and a JCPenney Mastercard. Although Synchrony issues both cards, the customer-service numbers differ.
The JCPenney Credit Card can primarily serve JCPenney purchases, while the Mastercard version can also work at merchants that accept Mastercard.
Therefore, check the card name or your most recent statement before calling. Doing so can help you reach the appropriate Credit Services department.
What Could a JCPenney Hardship Program Offer?
Synchrony may have account-assistance options for customers who experience financial hardship. However, the company does not publicly guarantee a particular reduced payment or interest rate for every JCPenney account.
As a result, the options available to one cardholder may differ from those available to another. Account status and current Synchrony policies can affect the assistance offered.
Instead of assuming specific terms, ask Credit Services to explain every option currently available for your account.
Questions to Ask About a JCPenney Hardship Program
First, ask whether Synchrony can reduce your required monthly payment. Next, determine whether any available arrangement changes the interest rate or fees on the account.
Additionally, ask how long the hardship arrangement lasts. You should also confirm when the first modified payment becomes due.
Finally, find out what happens after the assistance period ends. Understanding the entire arrangement can help you compare it with other repayment strategies.
Ask What Happens to Your JCPenney Card
Some creditor assistance arrangements may affect your ability to continue using a credit card. Therefore, ask whether Synchrony will restrict or close your JCPenney account while you participate.
Moreover, confirm whether your minimum payment could change again after the assistance period. You may also want to ask whether the repayment timeline becomes longer.
Write down the complete terms before accepting an arrangement so you can compare your options accurately.
Contact JCPenney Credit Services Before Falling Further Behind
If you expect difficulty making an upcoming payment, consider contacting Credit Services as early as possible. Addressing the problem sooner gives you more time to understand your options.
Additionally, explain whether your financial difficulty appears temporary or ongoing. That information can help the representative understand your circumstances.
Waiting until several accounts become seriously delinquent can create additional financial pressure. Therefore, early action may make the situation easier to address.
Look Beyond the JCPenney Hardship Program Payment
A smaller monthly payment may provide immediate breathing room. However, the payment amount should not be the only factor you evaluate.
For example, compare the interest rate, repayment period, total expected cost, and any account restrictions. Additionally, consider whether your other creditor payments remain affordable.
An arrangement that helps your JCPenney account may not solve the larger problem if several other cards continue to strain your budget.
When a JCPenney Hardship Program May Not Be Enough
A Synchrony payment arrangement may work well when your JCPenney account creates most of your financial difficulty. However, many consumers struggling with one card also owe several other creditors.
You might have JCPenney debt along with balances from Chase, Citi, Capital One, Discover, American Express, Wells Fargo, Bank of America, or another lender.
Consequently, reducing only the JCPenney payment may not lower your total monthly debt obligations enough to balance your household budget.
Managing JCPenney Along With Other Credit Cards
Calling every creditor separately can result in several different hardship arrangements. As a result, you may still manage different payments, interest rates, due dates, and program rules.
Instead, nonprofit credit counseling allows you to examine your complete financial situation. A counselor can review your income, expenses, JCPenney account, and other eligible unsecured debts.
That broader review can help determine whether individual creditor programs or one coordinated repayment strategy may provide a better solution.
How DebtWave Can Help Beyond a JCPenney Hardship Program
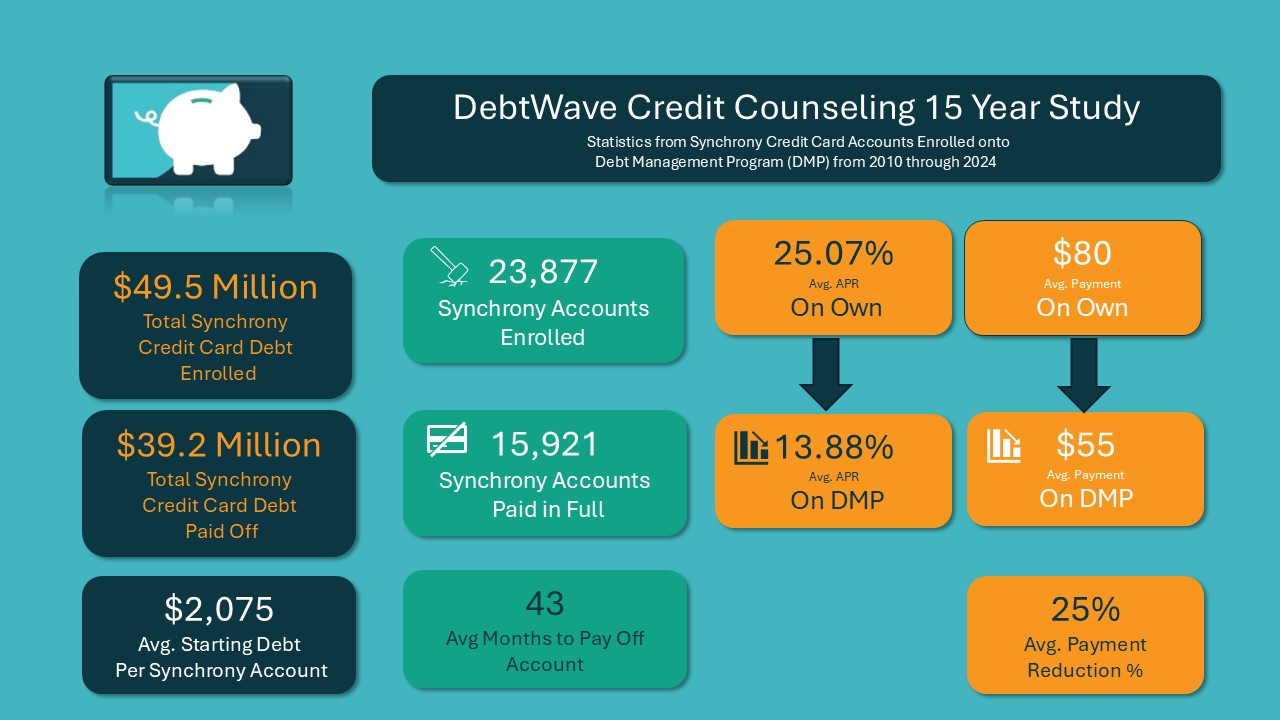
A Debt Management Program, commonly called a DMP, takes a broader approach than requesting assistance from only one creditor.
First, a DebtWave credit counselor reviews your overall financial situation. Then, we examine your creditor accounts and determine which eligible unsecured debts may qualify for the program.
Depending on creditor guidelines, participating creditors may provide reduced interest rates or other repayment concessions. However, individual terms can vary.
DebtWave Can Review Synchrony and Your Other Creditors
One advantage of nonprofit credit counseling is the ability to review every creditor affecting your budget. Therefore, your counseling session does not have to focus only on JCPenney or Synchrony.
DebtWave can evaluate eligible credit cards and other unsecured accounts to determine which debts may fit into a Debt Management Program.
Not every creditor or account will necessarily qualify. Nevertheless, reviewing your complete creditor list can provide a clearer picture of your repayment options.
One Debt Management Payment for Multiple Creditors
Qualifying clients generally make one monthly Debt Management Program payment for participating accounts. DebtWave then distributes the appropriate amounts to those creditors according to the repayment plan.
As a result, a DMP can simplify repayment when you currently manage several different credit card bills. Moreover, creditor concessions may make repayment more manageable.
A traditional DMP does not erase what you owe. Instead, the program focuses on repaying enrolled balances through a structured plan.
Can a Debt Management Plan Include JCPenney?
Potentially. DebtWave can review eligible Synchrony accounts to determine what Debt Management Program options may currently apply.
Additionally, we can evaluate your other creditors during the same review. That approach allows you to consider your JCPenney account as part of your complete financial picture.
Because creditor participation and concessions can change, DebtWave should review your specific accounts before you rely on any particular estimated payment or APR.
JCPenney Hardship Program vs. Debt Management Program
Both approaches may provide help when credit card payments become difficult. However, they address different financial situations.
A JCPenney hardship arrangement through Synchrony focuses specifically on that account. In contrast, a DebtWave DMP can evaluate multiple eligible unsecured creditors.
Therefore, the better solution may depend on whether one credit card or several debts create your financial pressure.
Compare JCPenney Hardship Program and DMP Options
| Feature | JCPenney / Synchrony Assistance | DebtWave Debt Management Program |
|---|---|---|
| Accounts Reviewed | Your JCPenney account | Multiple eligible unsecured accounts |
| Who You Work With | JCPenney Credit Services / Synchrony | DebtWave credit counselors |
| Available Terms | Depend on Synchrony and your account | Depend on participating creditor guidelines |
| Monthly Process | Arrangement for your JCPenney account | One DMP payment for participating accounts |
| Primary Goal | Make the JCPenney account more manageable | Create a structured repayment strategy for multiple debts |
Estimate Your JCPenney DMP Payment and APR
Before choosing a repayment strategy, it helps to compare the numbers. Therefore, DebtWave created a free Debt Management Plan Calculator.
The calculator can estimate what your monthly DMP payment and APR might look like based on the accounts you enter. Additionally, you can include several creditor balances to evaluate your complete debt situation.
Although calculator results cannot guarantee final creditor concessions, they can provide a useful starting point for comparing your options.
See What Your DMP Payment and APR Might Be
Enter your credit card balances to estimate your potential monthly payment and APR.
Compare a JCPenney Hardship Program With Your DMP Estimate
If Synchrony offers you a payment arrangement, compare that proposal with your DebtWave calculator results. First, review the monthly payment required under each option.
Next, compare the potential interest cost and expected repayment period. Additionally, consider how your other creditor payments fit into each strategy.
Finally, calculate your total monthly payments across all of your debts. That amount may provide a clearer measure of overall affordability.
Get a Personalized Review of Your JCPenney Credit Card Debt
If the calculator suggests that a Debt Management Program may help, DebtWave can review your situation in greater detail. You do not need to determine your eligibility before contacting us.
Instead, provide information about your JCPenney account and your other creditors. A counselor can then review your balances, income, expenses, and current payments.
Consequently, you can compare your existing repayment strategy with potential debt management options.
Request Help With Your Credit Card Debt
Complete the form below to learn more about DebtWave’s credit counseling and Debt Management Program.
DebtWave Is an NFCC Member Agency
Choosing a credit counseling organization is an important financial decision. DebtWave Credit Counseling is a member of the National Foundation for Credit Counseling (NFCC).
The NFCC maintains a nationwide network of nonprofit credit counseling agencies. Additionally, NFCC member agencies help consumers evaluate budgets, financial goals, and debt repayment strategies.

How an NFCC Debt Management Plan Can Help
Consumers participating in a Debt Management Program generally make one monthly program payment for participating accounts.
The credit counseling agency then distributes the appropriate funds to those creditors. Furthermore, participating creditors may provide reduced interest rates or other concessions when their guidelines allow them.
Therefore, a DMP may provide another option when financial hardship extends beyond a single JCPenney or Synchrony account.
Why Credit Counseling Can Help Beyond a JCPenney Hardship Program
Contacting JCPenney Credit Services makes sense when you need assistance specifically with that credit card. However, credit counseling gives you an opportunity to examine your complete financial situation.
A DebtWave counselor can review your debts alongside your income and household expenses. Consequently, you can determine whether your total monthly debt payments fit within your budget.
Moreover, counseling can help you understand how debt management differs from consolidation loans, debt settlement, and individual creditor hardship arrangements.
When to Consider More Than a JCPenney Hardship Program
You do not have to wait until several accounts become seriously past due before exploring your options. In fact, addressing payment problems earlier may provide more flexibility.
Consider credit counseling when minimum payments consume too much of your monthly income. Similarly, a review may help when high interest charges prevent your balances from declining.
Managing several creditor payments can also make a coordinated repayment strategy worth exploring.
Signs a DMP May Work Better Than One JCPenney Hardship Program
A DMP may be worth considering if you can repay your debt but struggle with high interest rates or multiple monthly payments.
Additionally, you may benefit from a review if assistance on your JCPenney account does not create enough overall monthly relief.
Most importantly, compare your choices based on affordability, expected repayment time, total cost, and your complete financial situation.
JCPenney Hardship Program Frequently Asked Questions
Does Synchrony Issue the JCPenney Credit Card?
Yes. Synchrony Bank currently issues both the JCPenney Credit Card and JCPenney Mastercard.
Therefore, cardholders experiencing payment difficulty should generally work with JCPenney Credit Services and Synchrony regarding the credit account.
What Number Should I Call for JCPenney Credit Card Help?
JCPenney currently lists 1-800-542-0800 for JCPenney Credit Card account questions.
If you have the JCPenney Mastercard, the current Credit Services number is 1-866-227-5213.
Does Synchrony Offer Hardship Assistance?
Synchrony encourages customers who need help making payments because of hardship to contact the company and discuss their situation.
However, available terms can vary by account. Consequently, ask for the specific assistance that may apply to your JCPenney card.
More JCPenney Hardship Program Questions
Can Synchrony Lower My JCPenney Credit Card Payment?
Synchrony may have account-assistance options for consumers experiencing financial difficulty. However, it does not publicly guarantee one reduced payment for every JCPenney cardholder.
Therefore, ask the representative for the exact payment amount and duration of any arrangement offered to you.
Can a JCPenney Hardship Program Lower My Interest Rate?
Available hardship terms depend on the account and Synchrony’s current policies. Consequently, ask whether an interest-rate adjustment applies to your JCPenney card.
Additionally, confirm whether the interest rate changes again after any assistance period ends.
Will a JCPenney Hardship Program Close My Card?
Account treatment can depend on the assistance arrangement. Therefore, ask whether Synchrony will leave the account open, restrict it, or close it before accepting a plan.
JCPenney Credit Card and Mastercard Questions
Is the JCPenney Mastercard Different From the Store Card?
Yes. Both cards connect to the JCPenney credit program, but the JCPenney Mastercard can also work anywhere Mastercard is accepted.
Additionally, JCPenney provides different Credit Services phone numbers for the traditional JCPenney Credit Card and the Mastercard.
Can I Manage My JCPenney Card Online?
Yes. Synchrony provides online account access for JCPenney cardholders, including account management and bill payment.
For example, customers can use Synchrony’s JCPenney account page to sign in, manage the account, and make payments.
Should I Call Before Missing a Payment?
Yes. If you expect an upcoming payment to become unaffordable, contacting Credit Services early gives you time to learn which options may be available.
Moreover, early action allows you to compare creditor assistance with other debt repayment strategies before the situation becomes more difficult.
JCPenney Hardship Program and Debt Management FAQs
Can a Debt Management Program Include JCPenney?
Potentially. DebtWave can review eligible Synchrony accounts to determine which Debt Management Program options may currently apply.
Because creditor guidelines can change, an individual account review provides more useful information than relying only on general estimates.
Can DebtWave Help With My Other Credit Cards Too?
Yes. DebtWave can review your complete creditor list when evaluating your financial situation.
Depending on creditor participation and account eligibility, a DMP may address multiple unsecured debts. As a result, you can look beyond only your JCPenney balance.
More Questions About Debt Management
Does a DMP Forgive My JCPenney Balance?
A traditional Debt Management Program generally focuses on repaying enrolled balances rather than settling them for less than the amount owed.
However, participating creditors may provide concessions that make repayment more manageable.
Is a Debt Management Program a New Loan?
No. A traditional DMP does not require you to borrow additional money to pay off your existing credit cards.
Instead, qualifying clients generally make one program payment for participating accounts, and DebtWave distributes the appropriate funds to those creditors.
How Can I Estimate My Debt Management Payment?
Use DebtWave’s free Debt Management Plan Calculator. Enter your debts to estimate what your potential monthly payment and APR might look like.
Take the Next Step Beyond a JCPenney Hardship Program
A JCPenney hardship program through Synchrony may provide useful assistance when your credit card payment becomes difficult to afford.
However, one creditor arrangement may not solve the larger problem if several balances strain your budget. Therefore, consider your complete debt picture before selecting a repayment strategy.
Start with the DebtWave Debt Management Plan Calculator to estimate your potential payment and APR.
Talk With DebtWave About Synchrony and Your Other Creditors
After using the calculator, contact DebtWave if you would like help reviewing your JCPenney or Synchrony account alongside your other debts.
A credit counseling session can help you compare your current payments with potential debt management options.
Ultimately, reviewing all of your creditors together can help you make a more informed decision about the repayment strategy that fits your budget.
Important Information About the JCPenney Hardship Program
Important: Synchrony payment-assistance programs, eligibility requirements, payments, interest rates, fees, and other account terms can change.
Individual results vary by consumer and account. DebtWave does not control JCPenney or Synchrony hardship and payment-assistance policies.
DebtWave calculator results are estimates and do not guarantee creditor participation, interest rates, payment reductions, savings, concessions, or Debt Management Program eligibility.