If your USAA credit card payment has become difficult to manage, you may have several options before missing a payment.
Fortunately, USAA offers resources for members who face financial difficulty, while military-specific protections may provide additional assistance in certain situations.
In addition, DebtWave's free Debt Management Plan Calculator can estimate what your USAA payment and APR might look like on a DMP.
USAA Credit Cards and the Military Community
USAA serves military members, veterans and eligible family members through banking, insurance and other financial services.
Credit cards come from USAA Federal Savings Bank, so account documents may reference either USAA Bank or USAA Federal Savings Bank.
Because military life can involve deployments, PCS moves and changes in household income, understanding available financial-assistance options can be especially important.
Why USAA Credit Card Debt Can Become Difficult to Pay
Credit card interest can make a balance expensive when you carry debt from month to month.
Moreover, even a manageable balance can become harder to repay when military moves, family expenses or changes in income reduce the amount available for debt payments.
Therefore, check the APR on your latest USAA statement before comparing hardship assistance, SCRA benefits or a Debt Management Program.
Does USAA Have a Credit Card Hardship Program?
No single publicly advertised USAA Credit Card Hardship Program guarantees the same payment, APR or repayment period for every member.
However, USAA has offered qualifying members payment assistance and deferments during certain financial hardships, including government shutdowns and catastrophic events.
For example, USAA has provided temporary credit card payment deferrals to eligible members during some government shutdown assistance programs.
Because assistance varies by circumstance, contact USAA and ask what options currently apply to your account.
Important: Do not assume every USAA member will receive the same payment reduction, APR, deferment period or fee waiver.
Instead, ask for the exact terms available on your account before accepting an arrangement.
Active-Duty Military? Check SCRA Before Choosing a DMP
Active-duty service members should first determine whether the Servicemembers Civil Relief Act applies to their USAA debt.
Federal SCRA protections can limit interest to 6% on qualifying obligations that you incurred before military service.
Moreover, USAA states that it goes beyond the federal requirement by limiting interest to 4% on qualifying USAA accounts.
As a result, an eligible service member may already have access to a rate that is more favorable than an ordinary hardship arrangement.
Why SCRA Benefits Should Be Reviewed First
Qualifying pre-service debt deserves special attention before you refinance, consolidate or restructure it.
Replacing an eligible obligation could affect protections associated with the original debt. Therefore, understand your military benefits before making a permanent change.
Who May Qualify for SCRA Credit Card Benefits?
SCRA generally focuses on qualifying financial obligations you incurred before entering military service.
In addition, certain Guard and Reserve members may receive protections when their service meets applicable requirements.
Because eligibility depends on both the debt and your military status, review USAA's SCRA information or speak with a military legal-assistance resource before changing qualifying pre-service debt.
How to Ask USAA for Credit Card Hardship Assistance
If you cannot comfortably make an upcoming payment, contact USAA and explain your financial situation before the account becomes more difficult to manage.
Before calling, gather your current balance, APR, minimum payment, household income and essential monthly expenses.
Then ask whether USAA can offer payment assistance, a temporary deferral, reduced payments or another hardship option for your account.
Finally, request written details so you can compare the offer with your other choices.
Questions to Ask USAA Before Accepting Payment Assistance
- What will my required monthly payment become?
- Will the APR on my account decrease?
- How long does the arrangement remain in effect?
- Are any fees reduced or waived?
- Does interest continue during a payment deferral?
- Could USAA restrict or close the credit card?
- How might the arrangement affect credit reporting?
- What happens if I miss an agreed payment?
- Does SCRA or another military benefit apply to this debt?
Estimate Your USAA Debt Management Plan Payment & APR
Comparing USAA's assistance with a Debt Management Program can help you understand which option may better fit your budget.
To begin, select USAA from the creditor list below.
Next, enter your current balance, APR and minimum monthly payment.
The calculator will then provide an estimated DMP payment and interest rate. Because creditor terms can change, use the results as an estimate rather than a guaranteed offer.
What If USAA's Hardship Assistance Isn't Enough?
If USAA is your only difficult account, working directly with the bank may provide enough relief.
However, military households often manage several financial obligations at once, including credit cards, auto payments, relocation costs and family expenses.
As a result, lowering one USAA payment may not fix the entire household budget.
A nonprofit credit counseling session can review your eligible unsecured debts together and help you compare repayment strategies.
Can a USAA Credit Card Be Included in a Debt Management Program?
A USAA credit card may qualify for a Debt Management Program depending on current creditor participation terms and the account itself.
Instead of taking out a new loan, a DMP organizes eligible unsecured debts into a structured repayment plan.
In addition, participating creditors may provide reduced interest rates or monthly payments under their current program guidelines.
However, military members should compare any DMP estimate with SCRA benefits and assistance available directly from USAA before enrolling.
How a Debt Management Program Works for Military Households
Review Your Debts and Budget
First, a DebtWave counselor reviews your balances, APRs, monthly payments, household income and essential expenses.
Identify Eligible Creditors
Next, the counselor determines which creditors may participate and estimates your Debt Management Program payment.
Compare All Available Options
Afterward, you can compare those estimates with USAA assistance, possible SCRA benefits and other repayment choices.
Make One Scheduled Program Payment
If you enroll, DebtWave receives one scheduled program payment and distributes funds to participating creditors.
Work Toward Paying Off Your Debt
Finally, you follow the repayment plan while adjusting your household budget as military circumstances change.
DebtWave's Historical Results With USAA Credit Cards
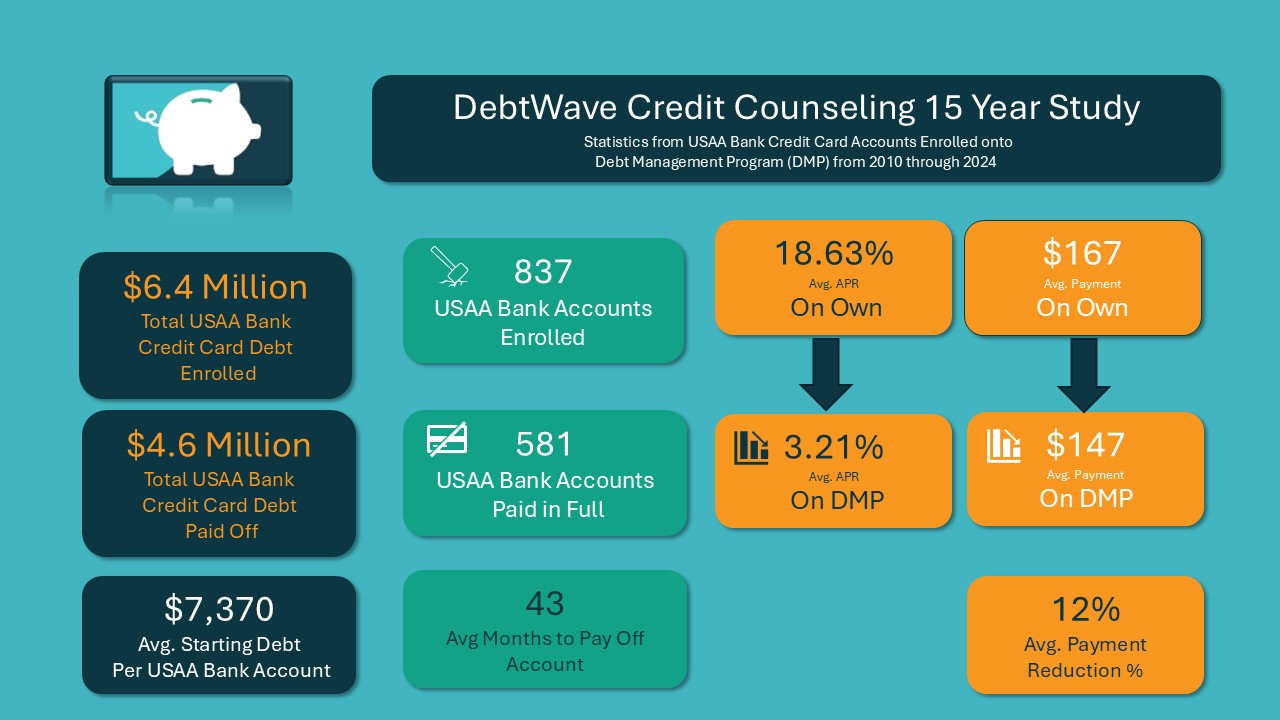
DebtWave studied USAA Bank credit card accounts enrolled in its Debt Management Program from 2010 through 2024.
The study included 837 USAA accounts with approximately $6.4 million in starting credit card debt. During the study period, 581 accounts reached paid-in-full status.
In addition, the accounts showed an average starting APR of 18.63% compared with an average DMP APR of 3.21%.
Historical average payments changed from $167 to $147, representing an average payment reduction of approximately 12%.
What Do DebtWave's Historical USAA Results Mean?
The study showed an average starting balance of $7,370 per USAA account.
Meanwhile, accounts in the historical study took an average of 43 months to pay off.
However, these figures describe past DebtWave results rather than guaranteed current terms.
Therefore, use the calculator or speak with a counselor for an estimate based on current creditor guidelines.
Historical results are not guaranteed. Creditor policies, eligibility requirements, interest rates, payments and Debt Management Program terms can change.
Your individual results will depend on your accounts, household budget and the creditor terms available when you enroll.
Free Financial Counseling Resources for Military Members
Military members also have access to financial resources outside of DebtWave and USAA.
For example, Military OneSource provides free financial counseling for eligible service members and family members.
In addition, installation financial readiness offices can help with budgeting, debt repayment and military-specific financial concerns.
These services can complement nonprofit credit counseling when you want another perspective on military benefits or financial protections.
Military OneSource Financial Counseling
Military OneSource offers financial counseling for eligible service members and family members.
Moreover, counselors can help with budgeting, debt repayment and communication with creditors.
For additional assistance, Military OneSource can be reached at 800-342-9647.
USAA Hardship Assistance vs. SCRA vs. a Debt Management Program
USAA account assistance works directly with the bank and may make sense when one USAA account is your main financial concern.
By contrast, a Debt Management Program can address multiple eligible unsecured creditors through one structured repayment plan.
Meanwhile, SCRA provides military legal protections for qualifying obligations rather than operating as a debt-management product.
Therefore, service members with qualifying pre-service debt should review SCRA benefits before replacing or restructuring that debt.
| Feature | USAA Assistance | SCRA Benefits | Debt Management Program |
|---|---|---|---|
| Who provides it? | USAA | Federal law plus applicable creditor benefits | Nonprofit credit counseling organization |
| Main purpose | Account-specific payment assistance | Military financial protections | Structured debt repayment |
| Accounts covered | Applicable USAA accounts | Qualifying obligations | Multiple eligible unsecured creditors may participate |
| Possible APR benefit | Depends on USAA's offer | Federal cap of 6%; USAA states 4% for qualifying accounts | Depends on participating creditor terms |
| New loan required? | No | No | No |
| Best starting point | Contact USAA | Check eligibility for qualifying pre-service debt | Review your complete unsecured debt picture |
Can You Pay Off USAA Credit Card Debt on Your Own?
You may be able to repay USAA credit card debt without a formal program when your budget has enough room.
First, reduce new credit card purchases whenever possible and list each card's balance, APR, minimum payment and due date.
Next, direct extra money toward the highest-interest balance or use a smallest-balance strategy if that method keeps you motivated.
However, if required payments remain unaffordable after reducing discretionary expenses, consider contacting the creditor or a counselor before falling further behind.
Plan for PCS Moves, Deployments and Military Transitions
Military finances can change quickly during a PCS, deployment, separation, retirement or transition to civilian employment.
Therefore, build your repayment plan around income you can reasonably expect instead of temporary allowances or uncertain future pay.
In addition, keep enough emergency cash for essential moving, transportation and family expenses rather than directing every available dollar toward unsecured debt.
A sustainable monthly payment usually works better than an aggressive amount that becomes impossible to maintain.
When Should a Military Member Talk With a Credit Counselor?
Consider nonprofit credit counseling when several minimum payments strain your budget, balances decline slowly or high APRs consume too much of each payment.
Likewise, a counseling session can help when your accounts remain current but an upcoming deployment, PCS or income change may make future payments more difficult.
Most importantly, compare the available options before committing to a new loan, debt settlement program or other major financial change.
See What Your USAA Payment & APR Could Be
Enter your USAA balance, current APR and minimum payment into DebtWave's free Debt Management Plan Calculator to see an estimated DMP payment and interest rate.
No new loan. Free estimate. No obligation to enroll.
Frequently Asked Questions About the USAA Credit Card Hardship Program
Does USAA offer hardship assistance for credit cards?
USAA does not publish one universal hardship plan with guaranteed terms for every member. However, USAA has provided payment assistance or deferments during certain qualifying financial hardships. Therefore, contact USAA and ask which options currently apply to your account.
What number should I call if I cannot afford my USAA payment?
Contact USAA Credit Card Services using the number shown on the back of your card or account statement. Before calling, gather your balance, APR, minimum payment, income and major monthly expenses so you can discuss the situation clearly.
Are lower interest rates available to active-duty military members?
Qualifying service members may receive SCRA protections on eligible pre-service debt. In addition, USAA states that it voluntarily limits interest to 4% on qualifying accounts, which is below the federal SCRA cap of 6%. Because eligibility requirements apply, confirm your benefits directly with USAA.
Can a USAA credit card qualify for a Debt Management Program?
A USAA credit card may qualify depending on current creditor participation terms and account details. Therefore, DebtWave's calculator can provide an estimate, while a counselor can review the current terms before you decide whether to enroll.
What DMP interest rate might USAA offer?
The exact rate depends on current creditor guidelines and the individual account. Historically, DebtWave's 2010–2024 USAA study showed an average DMP APR of 3.21%, compared with an average starting APR of 18.63%. However, past results do not guarantee today's rate.
USAA Debt Management and Military Benefit Questions
Will using the DMP calculator affect my credit score?
No credit check is required simply to use DebtWave's calculator. Instead, you manually enter your USAA balance, APR and current payment to receive an estimate.
Should active-duty members check SCRA before enrolling in a DMP?
Yes, especially when the debt may qualify as a pre-service obligation. Because SCRA can provide valuable interest-rate protections, compare those benefits before restructuring an eligible account.
Does Military OneSource provide financial counseling?
Yes. Military OneSource offers free financial counseling to eligible service members and family members, including help with debt repayment, budgeting and communication with creditors. Installation financial readiness offices may provide additional military-specific assistance.
What happens to my USAA credit card on a DMP?
Creditors generally close or restrict revolving credit cards included in a Debt Management Program, although treatment can vary by account and creditor policy. Therefore, ask your counselor what to expect before enrolling.
Is DebtWave affiliated with USAA or the Department of Defense?
No. DebtWave Credit Counseling, Inc. is an independent nonprofit credit counseling organization and is not affiliated with USAA, the Department of Defense or Military OneSource. However, DebtWave can help you compare a DMP with other repayment options available to you.
Compare Your USAA Credit Card Repayment Options
You do not need to wait until your USAA account becomes seriously delinquent to understand your options.
Instead, compare any assistance USAA offers with applicable military benefits and your estimated Debt Management Program payment.
Free nonprofit credit counseling. No new loan. No obligation to enroll.