How to Budget Biweekly Paychecks and Pay Monthly Bills
Creating a biweekly budget can feel frustrating when bills arrive on different dates. Your paydays shift every month. However, your rent, mortgage, and credit card payments usually have fixed due dates.
Fortunately, a simple paycheck budgeting system can help you stay organized. You can divide expenses, cover upcoming bills, and build savings.
In this guide, we'll show you how to manage monthly bills with biweekly paychecks. Plus, we'll walk through an example using real numbers.

Why a Biweekly Budget Works Differently
A biweekly pay schedule provides a paycheck every 14 days. Therefore, most months include two paychecks, while two months typically include three.
By comparison, a twice-monthly schedule provides 24 paychecks annually. Biweekly employees generally receive 26 paychecks each year.
Annual Paychecks
Most biweekly employees receive 26 paychecks during a typical year.
Extra Paycheck Months
Usually, two months contain a third paycheck. However, the exact pattern depends on the calendar.
Days Between Paychecks
Because your paydays move, you'll need to plan around fixed bill due dates.
Important: Build your regular monthly spending plan around two paychecks. Then, assign a separate purpose to any third paycheck.
Five Ways to Manage Monthly Bills With Biweekly Paychecks
Plan for Three-Paycheck Months
A third paycheck creates an opportunity to improve your finances. However, that money shouldn't automatically become spending money.
Instead, consider building an emergency fund, paying down debt, or covering upcoming irregular expenses.
Split Your Housing Payment
Housing often represents your largest monthly bill. Therefore, set aside half the payment from each regular paycheck.
For example, reserve $750 per paycheck for a $1,500 mortgage. Then, make the full payment when it's due.
Pay Bills Before Their Deadlines
Early payments can reduce the temptation to spend bill money. However, check how your creditor applies early payments.
Always confirm the required minimum payment and current due date.
Create Two Paycheck Plans
Instead of relying only on a monthly budget, assign expenses to each paycheck.
Because bill due dates vary, the two spending plans may look different.
Save Your Remaining Money
After covering essential expenses, review your remaining balance. Next, transfer part of that money into savings.
If you carry expensive credit card debt, consider additional principal payments as well.
Separate Bill Money From Spending Money
One of the biggest biweekly budgeting mistakes involves spending money already needed for bills.
Fortunately, you can prevent this problem by creating a dedicated bill-payment account or savings category.
For example, transfer half your rent or mortgage payment every payday. As a result, the full amount should be ready when your next payment comes due.
A Simple Account Setup
- Checking: Pay everyday expenses and upcoming bills.
- Bill reserve: Hold money for larger monthly obligations.
- Savings: Prepare for emergencies and future expenses.
However, allow enough time to build your reserve initially. You may need to adjust your first few pay periods.
Mortgage reminder: Ask your lender before sending partial payments. Saving half internally is different from making a formal biweekly mortgage payment.
Build Your Monthly Budget Before Splitting Paychecks
First, list every expense, including its payment amount and due date. Additionally, include flexible categories such as groceries and transportation.
Our example household spends $3,712 monthly. Although its average monthly income exceeds those expenses, timing remains a challenge.
Monthly Spending Plan
| Expense | Due Date | Amount |
|---|---|---|
| Mortgage | 5th | $1,500.00 |
| Food / Groceries | Flexible | $400.00 |
| Car Payment | 25th | $375.00 |
| Car Expenses | Flexible | $200.00 |
| Credit Card #1 | 21st | $200.00 |
| Gas & Electricity | 1st | $150.00 |
| Credit Card #2 | 13th | $150.00 |
| Cell Phone | 28th | $120.00 |
| Auto Insurance | 5th | $85.00 |
| Student Loan | 18th | $80.00 |
| Entertainment | Flexible | $75.00 |
| Pet Care / Food | Flexible | $60.00 |
| Gifts | Flexible | $60.00 |
| Cable | 26th | $60.00 |
| Toiletries | Flexible | $40.00 |
| Alcohol / Tobacco | Flexible | $40.00 |
| Personal Care | Flexible | $40.00 |
| Clothing | Flexible | $30.00 |
| Laundry / Dry Cleaning | Flexible | $25.00 |
| Internet | 6th | $22.00 |
| Total Monthly Expenses | $3,712.00 | |
On paper, this household has a monthly surplus. However, its $1,500 mortgage consumes most of one $1,889.24 paycheck.
Consequently, the family needs a paycheck-by-paycheck spending plan. Otherwise, several bills could become difficult to pay on time.
Biweekly Budget Example: First Paycheck on the 9th
Suppose the household receives its next paycheck on the 9th. First, it reserves $750 for the upcoming mortgage payment.
Next, the family allocates money to bills and living expenses. Some payments may come due after the next payday.
However, setting those funds aside now prevents accidental spending.
Available Income
| Budget Category | Purpose | Amount |
|---|---|---|
| Mortgage Reserve | Next month's payment | $750.00 |
| Credit Card #1 | 21st | $200.00 |
| Gas & Electricity | Upcoming bill reserve | $150.00 |
| Credit Card #2 | 13th | $150.00 |
| Student Loan | 18th | $80.00 |
| Flexible Expenses | Food, gas, and personal spending | $313.77 |
| Total Allocated | $1,643.77 | |
Because the family divided its expenses, it now has $245.47 remaining. Nevertheless, that amount should stay available for the next pay period.
Budgeting tip: Money assigned to a future bill should stay in your bill reserve. Don't treat reserved funds as extra spending money.
Biweekly Budget Example: Second Paycheck on the 23rd
Two weeks later, the household receives another $1,889.24. Additionally, it carries forward $245.47 from the previous paycheck.
Therefore, its available funds total $2,134.71. This paycheck covers the remaining mortgage reserve and several upcoming bills.
Income Plus Carryover
| Budget Category | Purpose | Amount |
|---|---|---|
| Mortgage Reserve | Completes $1,500 reserve | $750.00 |
| Car Payment | 25th | $375.00 |
| Gas & Electricity | Upcoming utility reserve | $150.00 |
| Cell Phone | 28th | $120.00 |
| Auto Insurance | Upcoming bill reserve | $85.00 |
| Internet | Upcoming bill reserve | $22.00 |
| Flexible Expenses | Food, gas, and other spending | $507.63 |
| Total Allocated | $2,009.63 | |
As a result, the household still has $125.08 after its planned allocations. More importantly, it has reserved the full mortgage payment.
These amounts illustrate cash-flow timing rather than a complete repeating annual budget. Actual allocations will vary with due dates and expenses.
How to Convert Monthly Expenses Into a Biweekly Budget
Flexible spending categories require a different calculation from fixed bills. For example, groceries and gas typically vary throughout the month.
To find the average biweekly equivalent, multiply the monthly amount by 12. Then, divide the result by 26.
Example: $400 Monthly Grocery Budget
$400 × 12 ÷ 26 = $184.62 per paycheck
Therefore, you can reserve approximately $184.62 from each paycheck for groceries.
However, fixed monthly bills require special attention. A two-paycheck monthly plan may need larger reserves to cover the bill before its due date.
Use Your Biweekly Budget to Build Savings and Reduce Debt
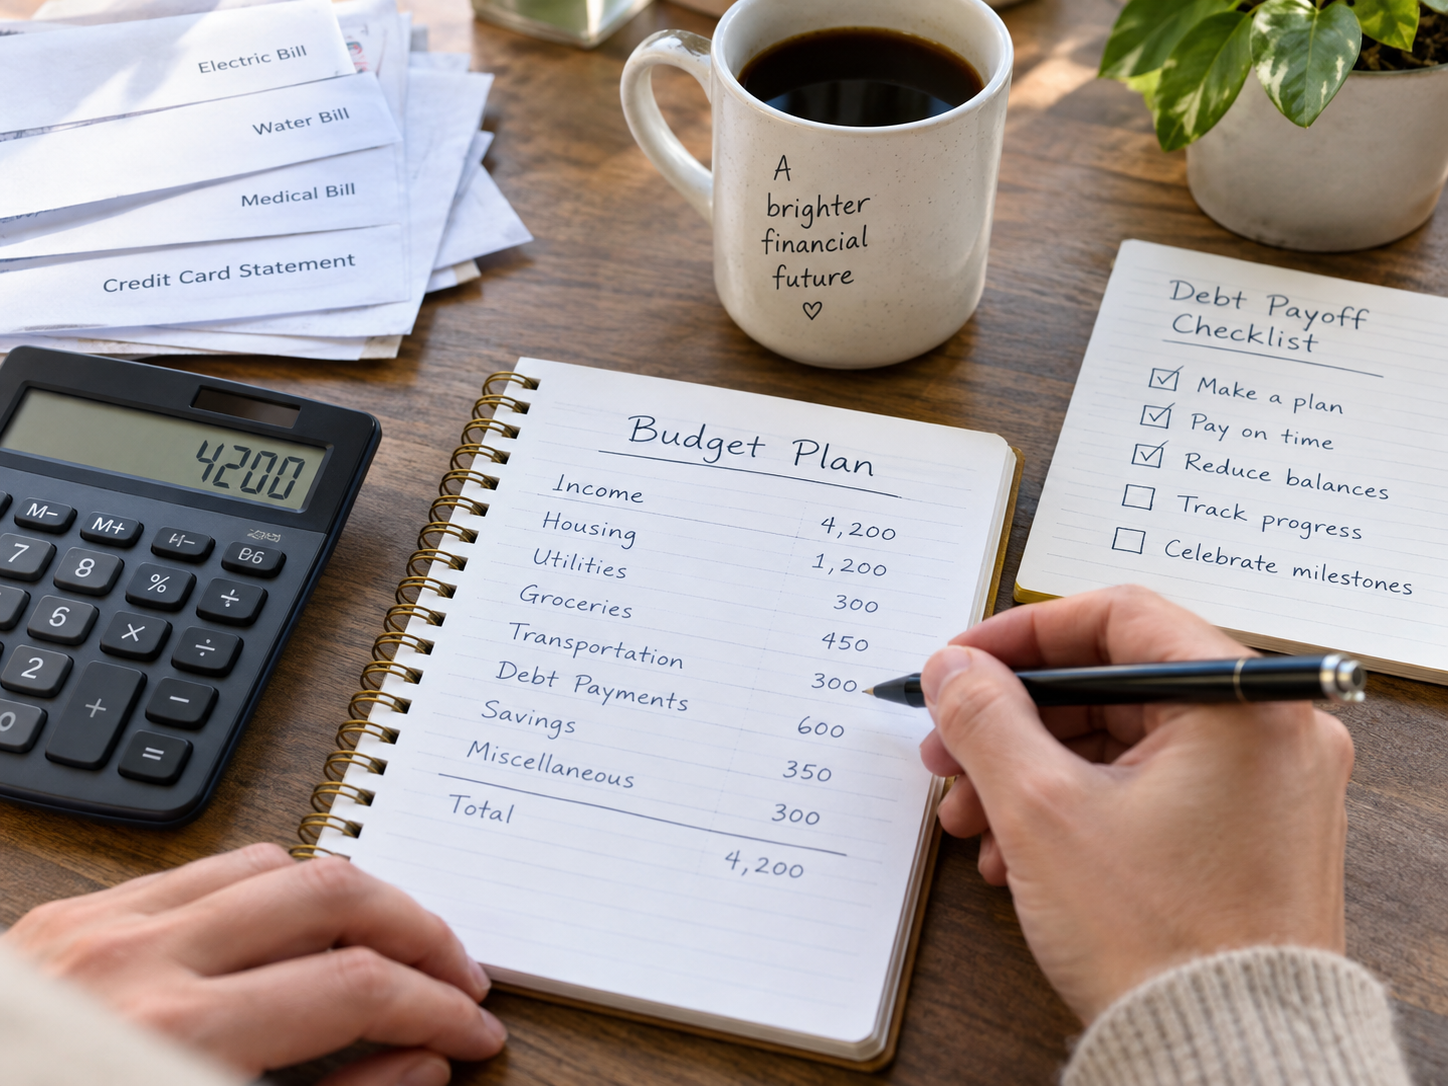
A successful biweekly budget does more than organize bills. It also helps you identify money available for your financial goals.
For example, a third paycheck may provide an opportunity to catch up on overdue bills. Alternatively, you could strengthen your emergency savings.
Build an Emergency Fund
Start with a manageable savings goal. Then, increase that amount as your financial situation improves.
Because unexpected expenses can disrupt your budget, even a small emergency fund provides valuable protection.
Reduce Credit Card Debt
High credit card interest can consume money each month. Therefore, consider directing extra funds toward high-interest balances.
However, keep enough cash available for essential bills and emergency expenses.
You can also explore DebtWave's credit card payoff calculator. It can help you estimate how different payments affect your repayment timeline.
What If Your Biweekly Budget Still Doesn't Cover Your Bills?
Sometimes, careful budgeting isn't enough to cover every financial obligation. For example, high credit card payments may leave little money for essentials.
Fortunately, nonprofit credit counseling can help you evaluate your options.
DebtWave's counselors can review your budget, debts, and monthly expenses. Additionally, they can explain whether a debt management plan may fit your situation.
A debt management plan may provide reduced creditor interest rates and one consolidated monthly payment. However, benefits depend on creditor participation and your circumstances.
Biweekly Budget Questions About Pay Schedules
Is biweekly pay the same as twice-monthly pay?
No. Biweekly employees generally receive 26 paychecks annually. However, twice-monthly employees receive 24 paychecks each year.
How many months have three paychecks?
Most biweekly schedules produce two three-paycheck months during a typical year. However, some calendar arrangements may create three such months.
Should I budget using two or three paychecks?
Generally, use two paychecks for your regular monthly bills. Then, treat a third paycheck as money for savings, irregular expenses, or debt repayment.
Biweekly Budget Questions About Monthly Bills
How do I split monthly bills between paychecks?
Start by listing amounts and due dates. Next, assign each expense to the paycheck that can fund it. Larger bills may require reserves from multiple paychecks.
Can I change my credit card payment due date?
Many credit card issuers allow due date changes. Therefore, ask your issuer whether a different date would better match your pay schedule.
Should I pay my mortgage every two weeks?
First, ask your mortgage servicer about approved payment options. Some arrangements may accelerate repayment. However, unofficial partial payments might not satisfy your monthly obligation.
Biweekly Budget Questions About Savings and Debt
What should I do with an extra paycheck?
Consider overdue bills, emergency savings, and high-interest debt. Additionally, prepare for irregular expenses such as car repairs or annual insurance premiums.
What if my expenses exceed my biweekly income?
First, separate essential expenses from optional spending. Next, review available assistance and creditor hardship options. If debt payments remain unaffordable, consider nonprofit credit counseling.
Can a biweekly budget improve my credit score?
A budget doesn't directly change your credit score. However, consistent on-time payments may help protect your payment history.
A Good Biweekly Budget Gives Every Paycheck a Purpose
The key to managing monthly bills with biweekly paychecks is planning ahead. Instead of reacting to due dates, assign each paycheck a clear purpose.
Start with your housing payment, essential bills, and everyday expenses. Then, reserve money for savings and future obligations.
As a result, you'll have a better understanding of where your money goes and what you can afford.
Thank you for your time and effort to write this article. Very reasonable and reassuring.
“Don’t be afraid to pay your bills early. If you got paid on the 9th and the bill isn’t due until the 20th, go ahead and pay it on the 9th. There’s no need to wait until the 20th to make a payment. If you wait until the 19th or 20th to pay it, you are giving yourself 10 days to possibly spend that money on something else. Paying your bills as soon as the money comes into your account will prevent you from wasting money on other non-necessities. This is especially true when they are payments, such as credit cards or car payments, that accrue interest. If balances are being carried, then interest compounds every day. Paying earlier allows you to pay less interest and pay off your cards faster.”
I take issue with this as my credit card through my bank doesn’t count it as a payment and they send me a late notice and charge me a fee. So, you may want to word this differently as it doesn’t apply to every bill.
[…] How to Juggle Monthly Bills With Biweekly Paychecks – DebtWave […]
[…] How to Juggle Monthly Bills With Biweekly Paychecks – DebtWave […]
[…] How to Juggle Monthly Bills With Biweekly Paychecks – DebtWave […]
[…] How to Juggle Monthly Bills With Biweekly Paychecks […]
[…] How to Juggle Monthly Bills With Biweekly Paychecks […]
Bi Weekly pay is just another thing that benefits the employers and screws over the employees. I used to get paid at the beginning of every month. It was great. I paid all my bills and then knew exactly how much money I have for the month to spend/save. When they changed I now did not have enough money to pay all my bills that were due. It started a chain reaction that I’ve never been able to recover from where I’m always paying my bills late.