If you’re struggling to make payments on your Macy’s credit card, you may be searching for information about the Macy’s Hardship Program.
The good news is that you may have options.
Credit card issuers sometimes provide hardship or payment-assistance options for customers experiencing financial difficulties. These options can potentially make payments more manageable while you work through a temporary financial setback.
But there’s an important question to ask before choosing a hardship program:
Is your Macy’s card the only credit card you’re struggling with—or is it one of several?
If Macy’s is your only problem account, contacting the card issuer about hardship assistance may make sense. But if you have balances with Macy’s plus Capital One, Chase, Discover, American Express, Target or other credit cards, nonprofit credit counseling may provide a more comprehensive solution for your overall credit card debt.
Here’s how the two options compare and what to do next.
Does Macy’s Have a Hardship Program?
Macy’s does not prominently advertise one standardized program called the “Macy’s Hardship Program” with guaranteed terms for every cardholder.
However, if you are experiencing financial hardship, you can contact the company servicing your Macy’s credit card account and ask whether financial hardship, payment assistance or reduced-payment options are available to you.
Macy’s credit card accounts are currently associated with Citibank, N.A. Macy’s lists credit card customer service at 1-888-257-6757. You can also call the number printed on the back of your Macy’s card or on your most recent statement.
Hardship options can vary based on your account and financial circumstances, so don't assume another cardholder's offer will be the same as yours.
What Can a Credit Card Hardship Program Do?
A credit card hardship program is generally designed to provide temporary relief when an unexpected financial event makes your regular payment difficult to afford.
Depending on the creditor and your situation, assistance could potentially include:
- A temporarily reduced interest rate
- A lower required monthly payment
- Waived or reduced fees
- A modified payment schedule
- Temporary restrictions on using the account
None of these benefits should be assumed or considered guaranteed. Ask the representative to explain exactly what assistance is available for your account.
Also ask how long the arrangement lasts and what happens when it ends.
That last question is important.
A hardship plan that makes your Macy’s payment affordable for a few months can be valuable if your financial problem is temporary. But if your budget is already stretched by several high-interest credit cards, temporary assistance on one account may not solve the larger problem.
How to Qualify for Macy’s Credit Card Hardship Assistance
There isn't one universal set of qualifications for every credit card hardship program.
Generally, creditors want to understand why you are having difficulty making your payment and whether a temporary change could help you get back on track.
Financial hardships may include circumstances such as:
- Job loss
- Reduced hours or reduced income
- Unexpected medical expenses
- Divorce or separation
- Death of a household income earner
- Emergency home or vehicle expenses
- Natural disaster
- Other significant changes to your income or necessary expenses
Contact the creditor as soon as you realize your payment may become difficult to afford. You do not necessarily want to wait until you've missed several payments to ask what options are available.
What to Have Ready Before You Call Macy’s
Preparing before your call can make the conversation easier.
Gather information about your:
- Monthly take-home income
- Rent or mortgage
- Utilities
- Food
- Transportation
- Insurance
- Medical expenses
- Loan payments
- Other credit card payments
- Macy’s credit card balance and payment
- Reason for your financial hardship
Most importantly, figure out how much you can realistically afford to pay each month.
You don't want to agree to a hardship payment that still doesn't fit your budget.
What Should You Say When Asking About the Macy’s Hardship Program?
You don't need a complicated script.
Try something like:
“I'm experiencing a financial hardship because of [briefly explain your situation]. I'm concerned about being able to continue making my current payment. Do you have a hardship or payment-assistance program that could temporarily lower my interest rate or monthly payment?”
If assistance is offered, don't immediately say yes.
Ask:
- What will my new monthly payment be?
- Will my interest rate change?
- How long will the program last?
- Are any fees waived?
- Will my account be closed or suspended?
- How will the account be reported to the credit bureaus?
- What happens when the hardship period ends?
- What happens if I miss a payment while enrolled?
Write down the representative's answers and request the terms in writing whenever possible.
When a Macy’s Hardship Program May Make Sense
Hardship assistance may be worth considering when:
- Macy’s is your primary problem credit card.
- Your financial hardship is temporary.
- You expect your income to recover soon.
- The new payment fits comfortably within your budget.
- The reduced payment or interest rate gives you enough breathing room to catch up.
For example, imagine your income was temporarily reduced but you expect to return to full-time work in several months.
A temporary reduction on your Macy’s account might provide exactly the help you need.
But there is another common situation.
You owe money not just to Macy’s, but to four, five or six different credit card companies.
Reducing one Macy’s payment may help—but you'll still have all of your other payments and interest charges to deal with.
That's when it may make sense to look beyond the Macy’s Hardship Program.
Have Multiple Credit Cards? Consider Credit Counseling
If you're struggling with several credit cards, a nonprofit credit counseling session can help you evaluate your entire financial situation rather than focusing on one account.
Credit counseling and a creditor hardship program are not the same thing.
With a creditor hardship program, you generally work directly with one creditor about one account.
During credit counseling, a counselor can review your:
- Macy’s credit card
- Other credit cards
- Interest rates
- Minimum payments
- Income
- Household expenses
- Overall budget
The goal is to determine what repayment strategy makes sense based on your entire financial picture.
At DebtWave Credit Counseling, the initial credit counseling session is free.
And talking to a counselor does not mean you are required to enroll in a debt repayment program.
A counselor can help you review the available options so you can decide what makes the most sense for you.
Macy’s Hardship Program vs. a Debt Management Program
For consumers with several high-interest credit cards, one option discussed during credit counseling may be a Debt Management Program (DMP).
A Debt Management Program is not a loan.
Instead, participating unsecured debts can be organized into a structured repayment plan. Creditors may provide concessions such as reduced interest rates or payments according to their individual guidelines.
Rather than making separate payments to several participating credit card companies, you make your scheduled DMP payment, and the credit counseling agency distributes funds to your creditors.
Here's the biggest difference:
| Macy’s Hardship Assistance | Debt Management Program |
|---|---|
| Focuses primarily on your Macy’s account | Can address multiple participating credit cards |
| Usually intended for a temporary hardship | Designed as a longer-term payoff strategy |
| Terms depend on what Macy’s/Citi offers | Terms depend on participating creditors and your plan |
| You deal directly with the creditor | A credit counseling agency helps administer the plan |
| May help if one card is the problem | May make more sense when several cards are the problem |
Neither option is automatically better for everyone.
The right question is:
Are you trying to fix one difficult Macy’s payment, or do you need a strategy for your entire credit card debt?
Why Credit Counseling May Be a Better Option for Multiple Credit Cards
Imagine you have balances with:
- Macy’s
- Capital One
- Chase
- Discover
- Target
You could call each creditor individually and ask whether it has a hardship program.
That may work.
But you may receive five different answers, five different payments, five different program lengths and five different sets of terms.
And some creditors may not offer you assistance at all.
Credit counseling approaches the problem differently.
Instead of asking, “How can I lower my Macy’s payment?”, you begin with:
“How can I realistically pay off all of my credit card debt?”
That distinction matters.
A lower Macy’s payment won't necessarily solve a $20,000, $30,000 or $40,000 credit card debt problem spread across multiple accounts.
A complete review of your budget and debts can help determine whether you can:
- Pay the balances off on your own;
- Use creditor hardship programs;
- Consider a Debt Management Program; or
- Explore another debt solution.
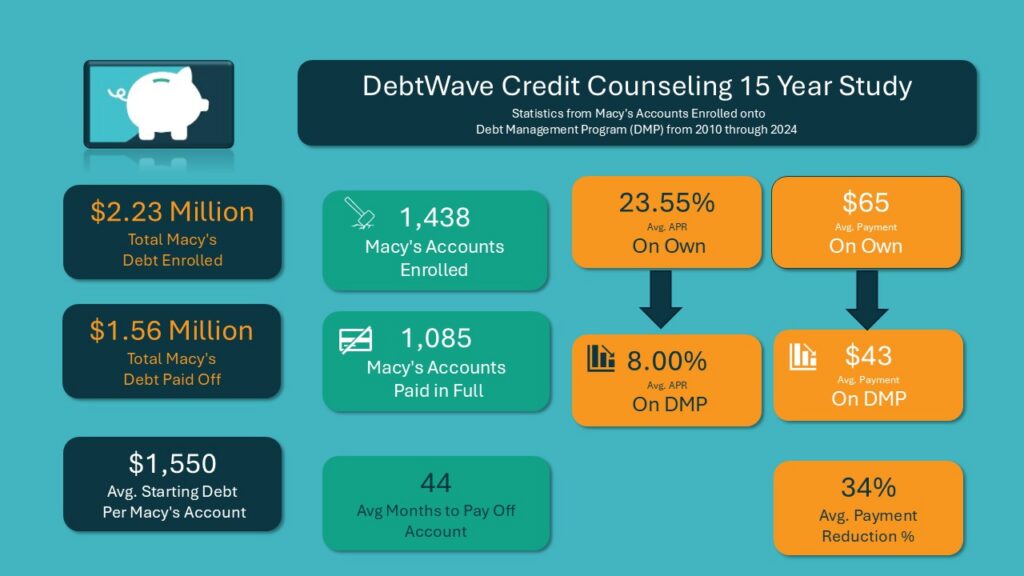
What Is a Debt Management Program?
A Debt Management Program is a structured repayment plan generally offered through a credit counseling organization.
It is not debt settlement, and it is not a debt consolidation loan.
You still repay the balances included in the program.
Participating creditors may agree to concessions that can make repayment more manageable. The exact terms depend on each creditor.
At DebtWave, Debt Management Programs typically aim to help clients become debt-free within approximately three to five years, although individual circumstances vary.
Credit cards enrolled in a DMP are generally closed, so you should understand that tradeoff before enrolling.
For someone whose goal is to stop relying on credit cards and systematically eliminate the balances, closing the accounts can also remove the temptation to continue adding new debt while paying off the old debt.
Should You Try Macy’s Hardship Assistance First?
You certainly can.
If the Macy’s card is causing the majority of your financial difficulty, calling the creditor directly is a sensible first step.
But look at your entire financial picture before making the decision.
Add up:
Total credit card balances: $______
Total monthly credit card payments: $______
Average interest rate: ______
Number of credit cards with balances: ______
Then ask yourself:
“If Macy’s lowered my payment tomorrow, would my overall credit card debt still be difficult to manage?”
If your answer is yes, the real problem may be bigger than your Macy’s account.
That's a good reason to consider speaking with a credit counselor.
Don't Wait Until the Problem Gets Worse
One of the most important steps you can take is simply taking action.
Ignoring high-interest credit card debt can make the problem harder to solve as interest charges accumulate and missed payments potentially lead to additional consequences.
Start by understanding exactly what you owe.
Make a list containing:
- Creditor
- Balance
- Interest rate
- Minimum payment
- Due date
Then decide whether your situation is a single-creditor problem or a multiple-credit-card problem.
If Macy’s is the only account causing trouble, contact Macy’s/Citi and ask what hardship options are available.
If Macy’s is just one of several credit cards you're struggling to pay, consider getting a complete credit counseling analysis before deciding how to proceed.
Get a Free Credit Counseling Session
Searching for the Macy’s Hardship Program is often the first step toward solving a larger credit card debt problem.
You may be able to work directly with Macy’s/Citi to make your Macy’s account more manageable.
But you don't have to evaluate every credit card in isolation.
DebtWave Credit Counseling is a nonprofit credit counseling organization and a member of the National Foundation for Credit Counseling. DebtWave can review your credit card debt, income and monthly expenses and help you understand the repayment options available to you.
The initial credit counseling session is free, and there is no obligation to enroll in a Debt Management Program.
If you have balances with Macy’s and other credit cards, a complete financial review can help you determine whether creditor hardship assistance, a Debt Management Program or another strategy makes the most sense.